Retail banking spent the past decade digitising the customer journey. The next phase changes something deeper: who, or what, makes and executes the decision. Artificial intelligence is moving from assisting customers and employees to interpreting intent, recommending actions, coordinating work and increasingly acting within defined limits.
Building the next retail bank will therefore require more than adding AI applications to existing systems. Banks will need data and infrastructure capable of supporting real-time decisions, orchestration layers that determine how systems work together, agents that can execute increasingly complex tasks, and clear rules governing what those agents are authorised to do. Payments, identity, cybersecurity and customer protection will need to evolve alongside them.
The commercial consequences could be equally significant. Intelligent agents may continuously compare products and providers, challenge customer inertia and alter how deposits, cards and other retail products are priced and distributed. Products themselves could move from predefined accounts and loans towards financial outcomes assembled around individual needs. As more decisions become automated, banks will also need to determine where human judgement remains essential and who remains accountable when machines act.
The question for financial institutions is therefore no longer simply where to use AI. It is what the next retail bank must look like, which decisions it should allow machines to make and execute, and what needs to change now to build it responsibly and profitably.
The AI in Retail Finance Conference brings together senior banking leaders, regulators, innovators and ecosystem players to examine these questions through TAB Global's annual research and assessment of leading retail financial institutions across the markets it serves. Hosted in Singapore, the Conference will bring evidence and perspectives from across the region into a one-day working discussion on how the next retail bank will be built and run.
How orchestration becomes the decision engine of the bank
Where agents should be allowed to act — and with how much autonomy
What happens to products, pricing and deposits when agents shop for customers
Who authorises agent-initiated payments and who is accountable when they fail
How identity, fraud and cybersecurity change as attackers become more automated
How boards and supervisors govern increasingly autonomous systems
How roles, management and skills change when people supervise agents

Central bankers, regulators and policymakers responsible for retail finance, payments, AI and digital identity
CEOs, country heads and chief retail, consumer and digital banking officers
Heads of retail AI, analytics and decision science
Heads of deposits, payments, cards, wealth, mortgages, consumer credit and financial wellbeing
Heads of customer experience, distribution, marketing, pricing and product management
Chief data, technology and AI officers; heads of enterprise architecture, innovation and transformation
Heads of fraud, financial crime, cybersecurity, risk, compliance and consumer protection
Board members and senior executives responsible for technology, AI and risk oversight
Founders and senior leaders from fintech, paytech, wealthtech, digital-bank, AI and identity companies
Senior executives from retailers, telecommunications companies, marketplaces, super-apps and other platforms embedding financial services
USD 999
Early bird : USD 500 (before 31 December 2026)
USD 1,500
Early bird: USD1,000 ( before 31 December 2026)
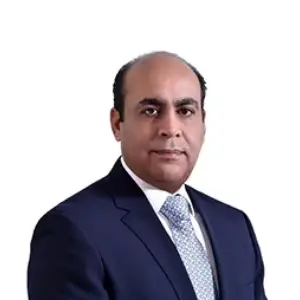
Former, Operating Partner SC Ventures, Ex MD, Corporate, Commercial and Transaction Banking, Standard Chartered
Jiten is a purpose-driven executive with over 30 years of leadership in global and regional markets, combining deep banking expertise with an entrepreneurial mindset. A former Operating Partner at SC Ventures and a long-time senior leader at Standard Chartered Bank, he has led transformative strategies across Asia, Africa, and the Middle East. Known for building inclusive financial ecosystems and driving innovation in transaction banking, Jiten now serves as a strategic advisor while continuing to shape the future of finance from his base in Singapore.

Co-Founder Remi Technology
Yong Cheng is a highly accomplished lead IT solution architect with deep expertise in fintech and artificial intelligence. With a strong track record in designing and implementing advanced technology solutions, Yong Cheng specializes in building scalable, secure, and efficient architectures that power innovation and digital transformation. Their comprehensive knowledge of AI-driven systems, cloud computing, and enterprise IT strategy enables the delivery of robust solutions that enhance business performance and elevate the customer experience. A visionary leader and strategic problem solver, Yong Cheng is committed to bridging technology and business needs to deliver impactful, future-ready outcomessolutions
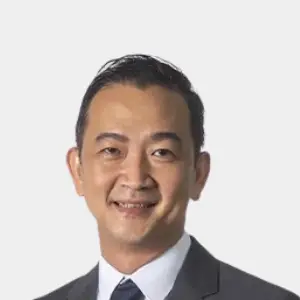
Chairman of Responsible Fintech Institute and Co-chairman of Digital Assets Association
A recognized fintech ecosystem builder, Chia Hock Lai brings nearly two decades of financial and technology expertise from organizations like GovTech and NTUC Income. He co-founded and led the Singapore FinTech Association (SFA) and Blockchain Association Singapore (BAS) and currently holds key roles at the International Digital Economies Association (iDEA), Responsible Fintech Institute (RFI), Digital Assets Association (DAA), and Global Fintech Institute (GFI). An NUS and NTU alumnus, Hock Lai is an IBF Fellow and SkillsFuture Fellow, recognized for his contributions to digital transformation. He actively advises startups and industry committees.
Research Director, TABInsights
Christian Kapfter is managing director of TAB Insights, the research arm of The Asian Banker and TAB Global. He has been the head of the Excellence in Retail Banking programme since 2008. TAB Insights, which has developed a rich repository of the data on the global digital banking industry, publishes the annual Digital Banking Ranking, the key findings of which will be shared in this programme. Christian also provides banks with internal benchmarking consulting services and help with their vendor selection exercises.
Other subject matter specialists are brought into the programme from time to time to tap their respective areas of specialty.
Chief Digital & Technology Officer, Partner, & Advisor
Axel Winter is a highly experienced technology leader with strong hands-on experiences in the banking, retail and start-up worlds. He was previously Global Head of Enterprise Architecture & Technology Strategy for Standard Chartered Bank and had similar roles at GE Money and Cisco Systems. He is currently the Chief Digital Officer for a luxury mall operator and advises start-ups in asset tokenization and eCommerce. His expertise in technology infrastructure for banks and large businesses makes him a valuable contributor.

Chairman, Wealth and Society
Gordian Gaeta has been an investment consultant for more than 25 years. He has advised and served many of the leading financial services organisations across Asia and close to half of the top 100 banks worldwide. He specialises in developing and implementing analytical solutions for complex strategic issues in financial services-related industries undergoing significant change or being exposed to intricate risk issues. He is currently the principal of Leopard Capital. As chairman, he convenes the advisory boards in their core function of validating the matrices used in the programmes ratings, rankings and awards to ensure that they are conducted in a professional, impartial and accountable manner.
Former International head of retail banking and Board Member
Wilson Chia is one of the most experienced digital bankers in the world with over 30 years as a career banker, mostly with Standard Chartered Bank in international positions. He currently advises CEOs of leading banks in emerging markets on digitalising traditional business lines. His strong financial background and expertise in balance sheet, funding, and product disciplines make him a valuable contributor to the program's operational areas.
Founder, TAB Global
Emmanuel Daniel is the founder of TAB Global which includes The Asian Banker, Wealth & Society, RadioFinance, The Banking Academy and The Skill Store. He is an award-winning writer and author with a background in management consulting. He previously served in several government advisory councils, interviewed some of the leading chairmen, chief executive officers, policy makers and entrepreneurs around the world and currently consults with banks on investor, media relations and strategy formulation. His recent book, The Great Transition - The personalization of Finance is Here, was published in September 2022.

Expert in SME Banking, Credit and Risk Management
Advisor, Excellence in Retail Financial Services Awards Programme, The Asian Banker
Andrew McRobert is a credit and risk management specialist in development, commercial and SME banking. He currently runs a training and consulting firm in SME and small business banking. He started his banking career in Citicorp and has also held various positions in commercial banking. Andrew had also worked in corporate finance at Price Waterhouse in Jakarta, Indonesia and has undertaken credit, problem loans and risk management assignments for the Asian Development Bank, IFC, African Development Bank and others. He has designed, written and presented financial markets seminars in nearly 30 countries in the Asia-Pacific, Middle East and African markets.

Chairman and Founder, Triple Bottom Line Investing (TBLI) Group
Member of Advisory Council, Wealth and Society
Robert Rubinstein, chairman and founder of TBLI Group, has been instrumental in building the environmental, social, and governance (ESG) and impact investing ecosystem, even before these terms were coined. He taught courses in sustainable finance at the Rotterdam School of Management from 2003-2006, and delivered numerous lectures at international business schools and universities throughout his career.
TBLI is a leading global ESG/impact investing network that has been educating, advising and connecting investors for 25 years.

Mr. David Gyori is a globally renowned fintech consultant, trainer, author and keynote speaker. He is the chief exefcutive officer of Banking Reports based in London and is a founding member of the World FinTech Association. Gyori is a faculty member of the Retail Banking Academy, one of the most prestigious banker-training facilities.
Founder and CEO, Alliance of Digital Finance Associations
Sarah has over 23 years’ experience, forming associations, networks, and communities, fostering forming strategic partnerships and collaborations, and leading continuous professional development. As the Founder and CEO of the Alliance of Digital Finance Associations (AllianceDFA), she is deeply passionate about and specializes in emphasizing the significance of networks, sharing knowledge, developing best practices, and fostering collaborative efforts to bring about innovation, efficiency, and social impact. Corley has fostered the formation of almost 20 digital finance/fintech associations across Africa and Asia and has created an Accelerator Program to promote their continual growth, maximise their impact, and ensure long-term sustainability.

EVP,WeBank
Joe Chen is currently the Executive Vice President (EVP) of WeBank. Founding member of WeBank (since April 2014), Chen is responsible for bank’s strategy, new business incubation and development including wealth management, Auto finance, SME lending, virtual credit card) and international partnerships. Head - Financial Market and FI division (since 2020), Chen is responsible for WeBank’s financial assets management, FICC, asset backed securitization and inter FI business. Partner (FIG) McKinsey Company 2005-2014 Chicago, Hong Kong, Taipei)
Managing Director, Financial Crime End to End Program, Standard Chartered Bank
Arjun Chib has over two decades of experience with Citi, ABN and SCB handling all Retail, BB and Wealth Products across Ops, technology, financial crime, risk, governance, digital, transformation, data standards and client journey. A thought leader with a proven track record in leading large scale transformation programs, new business growth, product and platform buildout and digitization. His core expertise lies in fostering collaboration within multicultural operations teams, often comprising close to 1000 members. Chib excels in leading significant transformations, guiding the transition from manual to digital operations, and creating seamless greenfield end-to-end digital client journeys.
CSO, Head of Strategy, Toss Bank
Mr. Kim started his career at MBC, Munhwa Broadcasting Corporation, after graduating from Yonsei University. He was a founding member of POOQ, an OTT service joint venture among the national broadcasting networks. During his career at MBC, he also founded another JV called SMR, which expanded the networks’ business into online video advertising. Mr. Kim then studied MBA at Columbia University. He joined Amazon.com as a senior product manager for Prime membership. There he led various projects including launching new Prime benefits and managed Prime price increases in US and EU. He conducted M&A deals and partnerships at SK telecom.
Author, “The Great Transition – the personalisation of finance is here”
Internationally renowned banking industry expert Emmanuel Daniel designed this programme for leaders entrusted with defining new frontiers in banking and responding to new technologies as they evolve. He is the author of "The Great Transition - The Personalization of Finance is Here" and the founder of TAB Global, which includes The Asian Banker, The Banking Academy, and TAB Insights amongst others. Emmanuel also advises leading banks in Asia and serves on government committees focused on the future of finance.
Chief Digital & Technology Officer, Partner, & Advisor
Axel Winter is a highly experienced technology leader with strong hands-on experiences in the banking, retail and start-up worlds. He was previously Global Head of Enterprise Architecture & Technology Strategy for Standard Chartered Bank and had similar roles at GE Money and Cisco Systems. He is currently the Chief Digital Officer for a luxury mall operator and advises start-ups in asset tokenization and eCommerce. His expertise in technology infrastructure for banks and large businesses makes him a valuable contributor.
Chief Digital & Technology Officer, Partner, & Advisor
Axel Winter is a highly experienced technology leader with strong hands-on experiences in the banking, retail and start-up worlds. He was previously Global Head of Enterprise Architecture & Technology Strategy for Standard Chartered Bank and had similar roles at GE Money and Cisco Systems. He is currently the Chief Digital Officer for a luxury mall operator and advises start-ups in asset tokenization and eCommerce. His expertise in technology infrastructure for banks and large businesses makes him a valuable contributor.
AI Operating Model and Enterprise Architecture Leader
Former Global Head, Standard Chartered
Axel Winter is a global technology and transformation leader with over 30 years of experience driving large-scale digital and AI-led change across banking, financial services, and platform businesses in Asia and Europe. At Standard Chartered, he led a US$1bn+ global technology and enterprise architecture agenda across more than 30 markets, shaping the bank’s digital, open banking, data, and AI strategy.
He is currently CEO of Xponential, building AI-powered SuperApp and SaaS platforms, and Chief Digital Officer at Siam Piwat Group, where he leads group-wide AI and digital transformation across customer experience, operations, and ecosystem platforms. Through Pivot Digital, Axel also advises boards and senior executives on practical AI adoption and enterprise transformation.
Axel brings an ecosystem and investment perspective as a Partner at Alpha Founders Capital, supporting fintech and AI ventures globally. His career spans senior roles at Cisco, GE Capital, Deloitte, Accenture, and Central Retail, combining deep banking expertise with hands-on experience in scaling AI and digital platforms.
Research Director, TABInsights
Christian Kapfter is managing director of TAB Insights, the research arm of The Asian Banker and TAB Global. He has been the head of the Excellence in Retail Banking programme since 2008. TAB Insights, which has developed a rich repository of the data on the global digital banking industry, publishes the annual Digital Banking Ranking, the key findings of which will be shared in this programme. Christian also provides banks with internal benchmarking consulting services and help with their vendor selection exercises.
Other subject matter specialists are brought into the programme from time to time to tap their respective areas of specialty.
Consulting Professor, Design Group, Stanford University
Barry Katz has authored eight books, including "Change By Design" with Tim Brown (Harper Collins, 2009/2019), which explores design thinking as a business strategy; "NONOBJECT" with Branko Lukic (MIT, 2010), a conceptual exploration of "the space between person and product;" "Make it New: The History of Silicon Valley Design," translated into Japanese, Chinese, Korean, and Spanish; and "Healthcare by Design" (University of Toronto Press). He is currently working on his new book, "The Architecture of Information: Structure and Symbol for the Age of Data." His writings on design as a strategy for innovation have been featured in numerous academic, professional, and popular journals. Additionally, Katz serves as a Professor of Industrial and Interaction Design at the California College of the Arts and is a Fellow at IDEO, Inc., a global design and innovation consultancy.
Principal, Global Capital Markets
Shawn Flynn brings a wealth of experience as a seasoned mid-market investment banker. Having established himself as a successful business owner in Beijing, China, Flynn returned to Silicon Valley to immerse himself in the dynamic startup ecosystem. His roles have been diverse, ranging from Head of Incubation for an AI and blockchain-focused incubator to President of the second oldest Angel group in the Valley. With an extensive background spanning various business stages and sectors, Flynn currently holds the position of Principal at Global Capital Markets, a premier middle-market investment bank. This bank specializes in services such as mergers and acquisitions, growth capital raising, and secondaries. Flynn's global perspective is further enriched by his proficiency in Mandarin and Spanish, languages he acquired during his nearly 8 years of living abroad.
Founder and CEO, IgniteGTM
Bill Barry stands out as an exceptional GTM (Go-To-Market) leader in the technology sector, boasting a proven track record of driving revenue growth for both established tech giants and high-potential startups. His unwavering pursuit of excellence, coupled with his talent for uniting diverse teams, has yielded staggering triple-digit growth trajectories and successful exits. By harnessing cutting-edge analytics and automating processes, Bill has earned a reputation as a revered advisor and mentor, renowned for consistently delivering exceptional results with an upbeat tempo.
With his robust technical background, strategic acumen, and remarkable interpersonal skills, Barry emerges as the top choice for businesses aiming to turbocharge their go-to-market capabilities and cultivate revenue engines. His profound grasp of the market landscape, combined with his ability to engineer and implement highly effective processes and systems, has established a pattern of unwavering success throughout his career.
Head Investor Relations, IgniteGTM
With a career spanning over 25 years as a registered investment banker and strategic consultant, Harold Graham is motivated by his commitment to supporting high-potential founders and connecting them with the most suitable capital partners. His expertise encompasses various industries, including technology, healthcare, and finance. Graham possesses a distinctive approach to fundraising that involves aligning the individual mission and goals of each startup. He understands that the success of fundraising extends beyond mere capital infusion; it involves a trifecta of strategic mapping, precise execution, and the cultivation of enduring alliances with investors. Throughout the intricate journey of fundraising, Graham expertly guides startups, helping them navigate the complexities, and securing the necessary resources to fuel their growth and innovation.
Co-Founder and CEO, Platina
Drawing from 25 years of industry experience in the telecommunications sector, Mark Yin has held esteemed leadership positions at renowned companies including Infinera, Ciena/Lightera Networks, Cisco, and Stratacom. Before co-founding Platina, Yin operated his independent consulting firm based in Asia, specializing in shaping strategies and investment directions for local Original Design Manufacturers (ODMs). Notably, he played a pivotal role as the inaugural VP of Marketing at Infinera (NASDAQ: INFN), a global pioneer in optical networking systems. During this tenure, he was instrumental in defining both current and future product lines, successfully launching the company, and subsequently establishing its influential presence in the Asian market.
Founder & CEO, knomee
Marla is a fintech founder, keynote speaker, and former executive at traditional wealth and asset management firms and leading transformational fintech providers. She led operational partnerships at BlackRock and J.P. Morgan quantified in the billions of dollars before leaping into fintech to improve customer experiences. She has built and scaled integration, channel, and corporate development partnerships at high growth fintech companies including Carta, Jemstep, Xignite, and Lending Club, innovating in the areas of private equity, digital advice, financial market data, and fixed income. She has experience as a client, a vendor, and a partner leading digital transformation in banking and capital markets, and as a change agent driving diversity and inclusion. She founded two women’s networks and speaks frequently on topics related to the evolution of financial services to broader audiences. In 2020, she was selected as a Silicon Valley Business Journal Woman of Influence, and was recognized in 2021 as a Woman in Wealth Tech to Watch.
Director of Business Development, BLAM Retail
Régine David's diverse expertise spans strategic partnerships in venture capital, finance, tech, art, non-profit, public, and private sectors. Prior to BLAM Retail, she directed business development at on-demand financial services firms, focusing on FinOps for private and public sectors. Her role emphasized revenue growth, retention, partnerships, and strategic branding. Régine also consults for startups on strategic partnerships, brand strategy, and business development. With a finance background, she built partnerships with advisors, founders, investors, and cohorts in the venture capital and tech ecosystem, offering guidance on internal and external business development.
Co-Founder/ Chief Digital Officer/ CTO, Iterate.ai
Brian Sathianathan’s career kicked off at Apple, initially chosen for his prowess in software development and encryption. During his 6-year tenure, he spearheaded iPhone and Intel Mac endeavors within the discreet New Product Introductions (Secret Products) Group. His key teams crafted the security and activation framework for the inaugural iPhone, resulting in his patent achievements. Subsequently, after an 8-year association, Brian departed Apple to establish Avot Media, which developed a video transcoding software used by major entities like Warner Bros. This venture culminated in its acquisition by Smith Micro [NASDAQ: SMSI]. At Smith, Brian ascended to head of the video division, steering strategy, vision, and integration.
Post his roles at Avot and Smith, Brian assumed a position on the seed-stage investment squad at Turner Media. Here, he scouted startups in Social, Consumer, Advertising, and Recommendation sectors, participating in 13 investments and a key acquisition (BleacherReport) across two years. Remarkably, two of his backed startups were subsequently acquired, including one by Apple.
Currently, Brian serves as Co-Founder and Chief Technology/Digital Officer at Iterate.ai, an innovation ecosystem initiated in 2013. Revered companies such as Ulta Beauty, The Pampered Chef, Driven Brands, and Circle K harness the "intelligent low-code" capabilities, a concept devised and patented by Brian and his team. This innovation, known as Interplay, significantly expedites and streamlines digital and AI-driven innovation. Notably frugal and highly efficient in capital usage, Iterate's revenues surged by 287% between 2017 and 2020.
CEO & Founder, LinkSV.com
Bob Karr is the CEO/Founder of Link Silicon Valley (LinkSV.com). He has been an active angel investor, an advisor to emerging internet companies, and a co-founder of the Angels Breakfast Club. Bob retired from a 30-year career in the corporate liability insurance business, during which he spent 15 years as a Partner at Dinner Levison Company and another 15 years as Senior Vice President of the Sedgwick Group. In these roles, he spearheaded business development and client services, exclusively focused on emerging and pre-IPO companies in Silicon Valley. Many of his emerging clients have transitioned into successful IPOs.
COO & Co-founder
A three-time entrepreneur with twenty plus years of business development, sales and marketing, Dawn currently leads day-to-day operations and product vision for Link Silicon Valley. She joined Bob in 2016 and led a total rebuild and relaunch of the website and SaaS offerings. Dawn started her career selling system software to Fortune 5000 firms and OEMs as chief rainmaker in her first company and went on to build a nationwide network of VARs and developers that doubled annual sales 3 years in a row. Dawn earned a BA in Economics at the State University of New York at Buffalo. She and her family now live on the San Mateo Coast.
Senior Managing Director, Newmark
Sherry Gubera is the senior managing director at the San Jose office, specializing in tenant representation for Silicon Valley tech companies. With vast industry experience, she optimizes facility acquisitions, dispositions, and lease restructures for startups and Fortune 1000 firms. Alongside her seasoned corporate real estate team, Sherry prioritizes lasting relationships and top-tier customer service. She's a trailblazer, holding Silicon Valley's first Leadership in Energy & Environmental Design (LEED) accreditation. Sherry authored Newmark's Green Handbook, a comprehensive guide for real estate professionals navigating green initiatives. At Newmark, she's completed 450+ assignments, advising tech, life science, and cleantech companies across 14.8 million square feet in lease and sale transactions.
Senior Managing Director, Newmark
Adam Green, Senior Managing Director at Newmark, joined in 2018 within the EMEA consulting practice of the Global Corporate Services division. He later moved to the global consulting team in 2020. With over 13 years of experience, Adam specializes in Integrated Workplace Services. His focus areas include workplace experience and planning, workplace technology solutions, outsourced service delivery, and facilities management. Adam excels in workplace strategy, change management, real estate consulting, technology-enabled workplace solutions, IoT, and program management. His leadership extends to vendor management and overseeing large teams.
Partner, Haynes and Boone
Roger Royse serves as a partner at Haynes and Boone, LLP's Palo Alto office, specializing in corporate and securities law, tax, and mergers and acquisitions. He provides counsel to a wide array of companies, spanning from nascent tech startups to publicly traded multinationals across various sectors. With the distinction of being a Fellow of the American College of Tax Counsel and a former chair of multiple committees within the American Bar Association Sections of Business Law and Taxation, Roger's legal expertise is highly regarded.
Furthermore, Roger's educational contributions extend beyond his legal practice. He has served as an instructor or professor for legal, tax, and business subjects at the Center for International Studies in Salzburg, Austria, Golden Gate University School of Law, and Stanford Continuing Studies. Nationally recognized as an authority in agtech (agricultural technology), Roger illuminates the legal landscape for companies operating in this domain.
Roger is the author of "10,000 Startups: Legal Strategies for Startup Success" and "Dead on Arrival: How to Avoid the Legal Mistakes That Could Kill Your Startup." His insights have garnered coverage in influential publications such as the Wall Street Journal, Forbes, Fox Business, Chicago Tribune, Tax Notes, Inc. Magazine, and many others.
SVP, Group Director, Innovation and Venture Banking Group, Flagstar Bank
Calina Thompson is the group director and senior vice president with the Innovation and Venture Banking Group at Flagstar Bank. She has over 18 years of experience working with Private Clients, entrepreneurs with a focus on startup, innovation, venture capital, and privately held businesses. Thompson also has expertise in the non-profit and private residential lending space. Prior to Flagstar, she was the senior relationship manager with First Republic Bank for 10 years.
CEO & GP, Portola Valley Partners
John Majeski brings a wealth of expertise encompassing startups, turnarounds, and major IT companies. Notably, he co-founded and played key roles in the success of 3 startups, all of which achieved successful exits. During his tenure at HP, he orchestrated the seamless integration of a company and fulfilled the role of CTO. At Dell, serving as VP/GM, Majeski not only successfully integrated a $1 billion acquisition but also remarkably propelled revenue growth from $400 million to $2.3 billion in a span of 3 years. During his time with Lenovo, he initiated and managed a global business endeavor aimed at acquiring technology, pivotal in steering Lenovo's transition from hardware to software and solutions. Majeski's leadership spans product, engineering, sales, and M&A domains.
Chair and Founder, RoseRyan Group
Kathy Ryan, Chair and Founder of RoseRyan Group, drives the firm's mission, strategy, and investments since co-founding it in 1993. She pioneered a flexible work-life balance model, now embraced by over 100 professionals at RoseRyan. After 26 years at the helm, Kathy appointed David Roberson as CEO in 2020, charting the firm's growth into a new era.
Kathy, known for her CEO and CFO experience with 50+ Silicon Valley startups, innovatively combined flexible work arrangements and a values-based culture at RoseRyan. She launched ventures like Bizinta, offering practice management software, and co-founded Kukuza Associates in 2019, specializing in cannabis accounting and finance.
Her leadership insights are sought after by industry and regional publications. The San Francisco Business Times recognized her as an influential woman in Bay Area business in 2015. Kathy appeared twice on Accounting Today's top 10 leaders list, known as the Managing Partner Elite. In 2012, the San Jose/Silicon Valley Business Journal named her one of the most influential women in Silicon Valley.
Enterprise Account Manager, Digital Realty (Silicon Valley Data Center)
Ray Ko has more than 18 years of experience in the data center and telecom space. Currently, he is assisting customers with best practices used in a data center to achieve digital transformation and optimal performance to meet their business demands globally.
CEO, HIA Technologies
Vacit Arat, CEO of HIA Technologies, is a seasoned serial entrepreneur with 25+ years of experience in operations and business development. Throughout his career, he has been at the forefront of pioneering new technologies, establishing viable businesses, and generating intellectual property (holding 22 US patents). His current venture, HIA Technologies, is the visionary force behind AIVIO™, an innovative digital assistant user interface revolutionizing healthcare communication.
AIVIO™ transforms the patient-provider dynamic beyond the confines of traditional office visits. This groundbreaking technology empowers healthcare providers with interactive digital representatives, enabling them to engage in sophisticated and empathetic conversations with patients. AIVIOs educate patients, address their inquiries about their condition, gather information through strategic questioning, and provide comprehensive interaction reports. The result: improved patient outcomes, enhanced communication, and cost savings.
CEO, Aggregage
Robert Flynn boasts a quarter-century legacy constructing and steering growth companies across internet and traditional media domains. He played a pivotal role in launching and overseeing Liquid Audio, a trailblazing venture that introduced a comprehensive software platform for lawful digital music distribution and commerce on the internet. His most recent endeavor involved being CEO and Co-Founder of Modern Feed & Supply, Inc., later rebranded as Clicker, ultimately acquired by CBS Interactive. In the interim, Flynn helmed Zetools, a pioneering software firm providing enterprise-grade solutions for IP video formatting, management, and distribution across all IP-based platforms through streamlined publishing. During his Zetools tenure, the company secured two Emmy Awards, and Flynn and his team earned recognition on Hollywood Reporter's Digital 50 list.
Director, Corporate Partnerships, Plug and Play
Allen Shi is a versatile professional excelling in corporate innovation and venture capital. Based in California, he's a driving force in cultivating strategic partnerships between corporations and emerging startups. Since February 2023, Allen has been pivotal at Plug and Play Tech Center, where he adeptly fosters alliances for mutual growth.
His previous role as Chief Revenue Officer at Brix Labs, an AI-driven engineering team management platform, underscores his adeptness in aligning technology with business goals. Prior roles, like Vice President at FTD Solutions LLC, showcased his proficiency in semiconductor facility systems and optimization. While serving as Chief Revenue Officer at LivNao, he demonstrated his commitment to mental health tech, despite the challenges the company faced.
Allen's affiliation with Plug and Play Tech Center spans years, progressing from Senior Director to Director of Corporate Partnerships. He's a key contributor to nurturing innovation ecosystems, with notable emphasis on Mobility, IoT, Energy, and Smart Cities.
Investor, Plug and Play Ventures
Davis Auksmukst is a seasoned Investor at Plug and Play Ventures based in Sunnyvale, California. With a diverse background spanning both finance and audit roles, Auksmukst has emerged as a vital contributor to the investment landscape.
In his current role, Auksmukst has accrued over five years of experience in cultivating strategic investments in groundbreaking technologies. His tenure at Plug and Play has been marked by a commitment to identifying and supporting innovative startups.
Prior to his venture capital endeavors, he showcased his financial acumen as an internal auditor at Luminor Group, an amalgamation of DNB and Nordea's Baltic operations. His role involved navigating intricate financial landscapes to ensure robust internal controls and adherence to industry standards. A significant part of Davis's journey includes his role as an Internal Auditor at DNB, where he exhibited his prowess in assessing and enhancing the efficiency of financial processes.
Head of Sales, OpenAI
Aliisa Rosenthal currently leads sales and partnerships at OpenAI, supporting enterprise customers building AI integrations into their products. Aliisa started her career in the field of artificial intelligence at Quid, where she held the role of director of strategic partnerships. She then moved on to become the first sales hire at Mixpanel, run enterprise sales at InVisionApp, and served as VP of sales at WalkMe.
Partner, Diaspora Ventures
Marvin Liao is is an Investor-Operator with a remarkable portfolio. As a partner at Rolling Fund Diaspora.vc and manager of the holding company Sukna Global, he wields a profound impact. His prior roles encompassed being a partner and board member at Game Groove Capital, an International Gaming Holding Company. Moreover, he held a significant role as a partner at Venture Capital Fund 500 Startups. There, he not only spearheaded the SF-based accelerator program but also steered investments in Seed stage startups. Throughout his tenure, he championed investments in over 414 pre-seed and seed stage startups.
His distinguished journey also features a decade-plus at Yahoo! as an executive, accumulating extensive operational experience across Asia, Europe, Latin America, and the United States. His reach extends further as he sits on the investment committees and advisory boards of various venture capital funds. Beyond this, he serves as a mentor to numerous accelerator programs globally.
Founding Partner, Blitzscaling Ventures
Chris Yeh has spent his entire career working at high-tech startups. His expertise include online advertising, online marketing, sales management, lead generation, product management, market research, product marketing, entrepreneurship, general management
Blitzscaling Ventures
I have been an active professional in the business and technology sectors in Silicon Valley. As a founder, CMO, industry analyst, and public speaker, I am passionate about discovering the next technology trend, explaining it, and helping it become deployed worldwide.
My career arc has spanned web2, sharing economy, web3, and autonomous/AI technologies. I examine emerging technologies in terms of growth, opportunity, and changing consumer behaviors and expectations.
I began my career as an analyst at Forrester Research and later transitioned to Altimeter Group as a Founding Partner. In 2013, I established Catalyst Companies to concentrate on the emerging collaborative economy and the maker movement. I also co-founded Kaleido Insights. In 2022, I took on the role of CMO at a web3 project called RLY Network Association, funded by a16z, Coinbase Ventures, Battery, and others.
I have appeared in publications such as The Wall Street Journal, The New York Times, USA Today, and Fast Company. I have published research reports, playbooks, and frameworks to help businesses navigate change, enhance customer experiences, and identify trends before they happen.
I frequently speak and present at conferences and events worldwide, including global conferences, corporate kickoffs, TED stages, Web Summit, and host events around the world.
Senior Director, IDEO
I have been an active professional in the business and technology sectors in Silicon Valley. As a founder, CMO, industry analyst, and public speaker, I am passionate about discovering the next technology trend, explaining it, and helping it become deployed worldwide.
My career arc has spanned web2, sharing economy, web3, and autonomous/AI technologies. I examine emerging technologies in terms of growth, opportunity, and changing consumer behaviors and expectations.
I began my career as an analyst at Forrester Research and later transitioned to Altimeter Group as a Founding Partner. In 2013, I established Catalyst Companies to concentrate on the emerging collaborative economy and the maker movement. I also co-founded Kaleido Insights. In 2022, I took on the role of CMO at a web3 project called RLY Network Association, funded by a16z, Coinbase Ventures, Battery, and others.
I have appeared in publications such as The Wall Street Journal, The New York Times, USA Today, and Fast Company. I have published research reports, playbooks, and frameworks to help businesses navigate change, enhance customer experiences, and identify trends before they happen.
I frequently speak and present at conferences and events worldwide, including global conferences, corporate kickoffs, TED stages, Web Summit, and host events around the world.
CEO, Managing Partner, Silicon Foundry
Neal Hansch, CEO and managing partner of Silicon Foundry, draws upon over 25 years of experience in venture capital, product management, technology operations, corporate development, and trusted advisory to steer the firm. Prior to this, he assumed the role of Managing Director for the emerging markets technology training, investment, and incubation program at the Meltwater Entrepreneurial School of Technology (MEST). In this capacity, he led a global team of 150+ professionals, orchestrated over twenty startup investments, and forged partnerships with industry giants like Google, Samsung, and Vodafone.
Neal's professional journey includes a tenure as General Partner at Rustic Canyon Partners (RCP), an early-stage VC fund managing $500 million. He also contributed to the corporate development group at Macromedia (Nasdaq: MACR, acquired by ADBE). In this role, he held responsibilities for global M&A transactions and strategic equity investments, gaining valuable insights into cross-border transactions through extensive travel across Asia.
Principal, Silicon Foundry
John Zamora, Principal at Silicon Foundry, serves as a versatile advisor to members spanning diverse industries, with a specific emphasis on financial innovation. He comes with a wealth of experience, having previously spearheaded strategy and operations at First Circle, a fintech startup in Southeast Asia backed by Series A funding.
His expertise is underpinned by a comprehensive background in investment management, global strategy consulting, and international development. Notably, his contributions have extended to organizations like AllianceBernstein, Albright Stonebridge Group, and USAID. Additionally, John holds FINRA Series 7 & 63 licenses, adding a regulatory dimension to his multifaceted capabilities.
SVP, General Manager, Arise Gaming
John Pompei serves as the Senior Vice President of Customer Success at Arise. His multifaceted role encompasses bolstering business development, orchestrating seamless implementations, and ensuring operational excellence for Arise Gaming clients.
Prior to joining Arise, he held the position of Chief Customer Officer at Officium Labs, overseeing sales, marketing, and service delivery. Preceding this, he was at the helm of global player experience at EA (Electronic Arts), served as DVP of Customer Operations for Sears & Sears Marketplace, and spent a significant 15-year tenure at Microsoft. During his time at Microsoft, he held various leadership positions, notably directing consumer support across Europe, Middle East & Africa, while simultaneously spearheading Global Skype Support.
John Pompei's impact extends beyond roles, as he's recognized as a thought leader in Customer Experience (CX). His strategies and solutions have resonated globally, blending technology and human elements to elevate customer experience. His teams have been acclaimed for their excellence in customer experience and support under his adept guidance.
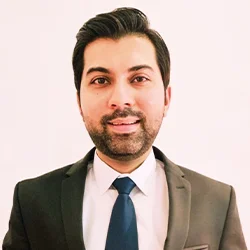
Chief Digital & Strategy Officer, NTT Data
Maaz Khan thrives at the intersection of technology, business, innovative startups, human-centered experiences, and social good. He possesses a talent for weaving captivating narratives and connecting dots through design thinking, data, and logic, compelling people to take action.
In his capacity, he advises enterprise startups and tech companies on digital strategy, transformation, partnerships, and innovative Go-To-Market approaches. Maaz is a versatile cross-functional leader, collaborating with NTT/Docomo Ventures portfolio firms and the Silicon Valley Ecosystem. His role encompasses strategic business development and fostering opportunities for a symbiotic relationship between NTT customers and partners.
Beyond his professional endeavors, Khan co-founded Global Youth Connection, a microfinance initiative, and played a foundational role in Ideatrr, an innovative ideation platform uniting the world through ideas.
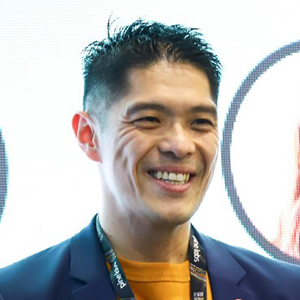
Chief Operating Officer
Singapore FinTech Association (SFA)
Reuben is Chief Operating Officer at Singapore FinTech Association (SFA). He leads the secretariat and works with the executive committee to spearhead initiatives that strengthen the FinTech ecosystem in Singapore. With over 18 years of experience in business development and management, Reuben has empowered both large enterprises, SMEs and government agencies in uncovering valuable revenue and growth opportunities through active business partnering and strong leadership. He has led teams across the industries of aviation, real estate investment, marine, intellectual property, amongst others.
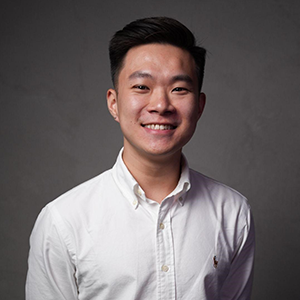
Chief Product Officer
Cake Group
Ng Ying Zhong is the CPO at Cake Group, one of the fastest growing digital assets innovators. Cake Group empowers investors to generate returns on their digital assets through decentralized finance (DeFi) services and applications in a secure and transparent way through its core businesses. Cake Group’s four verticals are Bake, its retail aim; Levain, its institutional arm; Birthday Research, its R&D arm; and Whisk, its VC arm. Zhong steers the key product verticals and research arm at Cake Group. From his initial role as the company's first product manager, he laid the foundation for Cake Group’s product management practice, driving its transformation into a product-led organization. With a dedicated team of over 50 product managers, engineers, and designers, Zhong continues to promote innovation and cultivate growth, facilitating the development of advanced solutions.
In 2022, he was also honored as a Singapore Fintech Leader Under 30, recognizing his significant contributions to the fintech space.
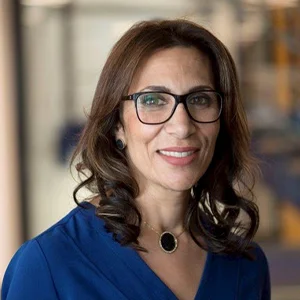
Centre Head
BIS Innovation Hub
Maha is Centre Head, BIS Innovation Hub Singapore. Having been newly appointed, most recently Maha was Head of Department for Early and High Growth Oversight leading the Financial Conduct Authority’s (FCA) response to the Kalifa review of Fintech. A Senior Leadership Team member, she is setting up this new department from the ground up as part of the FCA’s strategy. Prior to this, Maha served as Chief Payments Officer at Pay.UK on secondment from the FCA, responsible for running the payments operations of BACS, Faster Payments, Image Clearing Services and related managed services.
Maha joined the FCA in 2017 to set up the first Payments Department and was responsible for crafting and implementing the FCA supervisory strategy for the UK Payments Sector. This included leading the implementation of the Second Payments Services Directive (PSD2) and Open Banking.
Projects Manager & Advisor
BIS Innovation Hub – Singapore Centre
Benjamin Lee is the Projects Manager & Advisor for the Bank for International Settlements Innovation Hub (BISIH) in Singapore. He was seconded to the BISIH through the Monetary Authority of Singapore (MAS) and worked to establish and launch the centre, and to manage its projects pipeline. The BIS Innovation Hub is a joint initiative by the BIS and its partner central banks to identify and develop in-depth insights into critical trends in technology affecting central banking; develop public goods in the technology space geared towards improving the functioning of the global financial system; and serve as a focal point for a network of central bank experts on innovation.
Prior to this appointment, Lee spent most of his career in central banking at the MAS, where he worked on international finance matters, and at the Ministry of Finance in Singapore, where he worked on public finance administration matters. Lee has also served as Singapore's representative to the Executive Board of the World Bank Group and was based in Washington DC between 2014 - 2016.
Advisor
BIS Innovation Hub
Kah Kit is an Advisor at the Bank for International Settlements Innovation Hub (BISIH) in Singapore. He leads policy and governance work in next-generation financial market infrastructure projects such as Project Nexus which aims to interlink fast payment systems to enable instant cross-border payments. He also provides policy support for Project Mandala which seeks to develop compliance-by-design architecture to enhance cross-border payments. Aside from project contributions, he also represents the BISIH on the Governance and Oversight workstream of the Committee on Payments and Market Infrastructures (CPMI), providing insights and practical learnings to contribute to the G20 cross-border payments programme.
Kah Kit is a secondee from the Bank Negara Malaysia (BNM) with over 16 years’ experience ranging from legal advisory and prosecution of financial crimes to policy development in the areas of payments, fintech and digitalisation. At BNM, he was instrumental in spearheading Malaysia’s migration to digital payments and foster the development of interoperable real-time payments. He also led the Digital Currency Research Hub where he was responsible for developing policies and strategies on CBDC and digital assets.
Advisor
BIS Innovation Hub
Sonja is an Advisor at the Bank for International Settlements Innovation Hub (BISIH) Singapore leading the Hub’s central bank digital currency (CBDC) program. In this position, she leads project Mandala and co-leads project Mariana. Davidovic is seconded from the Monetary Authority of Singapore while on leave from the International Monetary Fund (IMF).
At the IMF, Davidovic worked as Economist and Digital Expert on Transformative Technologies. In that position, she provided capacity building, policy recommendations and technical advice to IMF member countries on digital currencies, including CBDCs. In addition to numerous analytical and research papers on financial technology and digital currencies, she also contributed to the analytical work for the G20 agenda to enhance cross-border payments. Immediately prior to joining the BIS, Davidovic worked as Market Infrastructure Expert on the digital euro investigation phase at the European Central Bank (ECB).

Ecosystem Development Manager
NUS Enterprise
A holistic marketer with more than 10 years’ experience in marketing and communication for, in particular, tech industry. Has a broad and integrated perspective in developing, designing and implementing marketing programs and activities.
Business Development Manager & CEO Liaison Officer
SSenStone
Taeyoung Kim (TK) is a professional with experience in finance and cyber security, currently serving as the Business Development Manager and CEO Liaison Officer at swIDch Ltd. Her previous roles at Lloyds Banking Group, Fujitsu Korea, and STX Offshore & Shipbuilding demonstrate her expertise in financial analysis, client relationship management, and compliance.
Chief Growth Officer
Bytesforce
Arun Sangwan currently holds the position of Chief Growth Officer at Bytesforce Corporation, a leading Insurtech based in Singapore. With a focus on sales, marketing, and partner ecosystems, he is dedicated to scaling up the business and expanding Bytesforce into new markets while strengthening partner relationships. Sangwan brings extensive experience from roles at Neutrinos and Citrix, where he demonstrated a talent for driving innovation and fostering strategic growth.
Regional Director
BLOCK71 Southeast Asia
Hui Hong Seow is a seasoned professional known for her achievements in entrepreneurship, policy development, and innovation. Currently, she serves as the Regional Director at BLOCK71 Southeast Asia, where her role involves ecosystem building and strategic operations. With a background that includes roles such as Venture Fellow at Insignia Ventures Academy and Head of Revenue at Ablr, Hui Hong has left her mark on organizations like MiRXES, BlueChilli Group, raiSE SG, SG Enable, and the Ministry of Trade and Industry (Singapore).
Director of Senior AI Solution, 4 Paradigm
Christine is the designer of the "4 Paradigm Delivery Standardisation of Project Management Performance", and the architect of the early-stage KEY for delivering AI projects in the 4 Paradigm, effectively putting "AI empowers business" into action. Christine has extensive experience in decision-making AI solutions and large-scale online service architectures, such as the Intelligent Real-time Banking Risk Control System and the Personalised Marketing System. She is also well-versed in developing applications for big data and machine learning systems.
Head of Data Science Team, 4 Paradigm
Mr. Li Bin was a Data Scientist at China PingAn Group Financial OneAccount from 2018-2020. He was responsible for the design and implementation of AI solutions for the financial industry. He served as the AI product manager in the company and successfully designed and launched AI capability products such as voiceprint signature and application material forgery recognition.
From 2020 to the present, he has been the head of the data science team at 4 Paradigm. He is responsible for the implementation of the "Polaris" experimental science business on the enterprise side. He has provided AI consulting and implementation services for several state-owned banks and joint-stock banks, covering key areas such as risk control, retail marketing, and customer service efficiency.
Chief Architect, Du Xiaoman Financial
Li Feng brings a wealth of experience in IT and the Internet to his role. He specialises in designing and researching financial distributed systems, middleware, and foundational platforms. His responsibilities extend to strategic planning and technology development at Du Xiaoman, where he has led the evolution of credit technology from 1.0 to 4.0, significantly boosting business growth.
In the field of fintech, Li Feng has spearheaded ground-breaking research and successful implementations in areas like blockchain, complex engineering technology, virtual reality, and IoT. Notably, he established Baidu's first-ever blockchain R&D team. His work has gained global recognition, including Forbes Global Blockchain 50, Harvard Business Review accolades, and recognition from the Ministry of Industry and Information Technology.
Li Feng is a distinguished industry expert who has actively contributed to national standards, authored various white papers and blue papers, and personally filed over 60 international and domestic invention patents.
Director of Financial Industry Solutions, JD Technology
Jiaoyao worked for multiple world-renowned companies such as Canon, ABeam Consulting, Yiqianbao (a mobile payment platform under PingAn Group), and China Construction Bank prior to joining JDT (JD Technology). With extensive cross-industry work experience in financial technology, the internet, consulting, and IT, he has a unique perspective on a wide range of subjects, including big data models, blockchain, inclusive finance, digital transformation, intelligent data platforms, digital marketing, and operations.
Executive Director and Vice President, MYbank
Mr. Jiang Hao has more than 20 years of experience in the financial industry. He previously served as the Senior Deputy Manager of China Construction Bank, Vice President of the Shanghai Branch of Bank of China (Hong Kong) Limited, Head of Retail Credit at Bank of Shanghai Head Office, Chief Compliance Officer of BOSC Asset, and Personal Banking Director of Bank of East Asia (China) Limited, among other executive roles. He joined MYbank as the Chief Compliance Officer in May 2018. He has served as the Secretary of the Board of Directors and the Chief Compliance Officer of MYbank since July 2020 and has served as the Vice President of MYbank since September 2021.
Co-CEO, LianLian International
Shen Enguang joined the company in September 2020 and held the positions of Vice President, Director of the Foreign Exchange Business Department, and Director of the International Financial Cooperation Department. He is currently co-CEO at LianLian International, overseeing foreign exchange business, B2B business management, international banking cooperation, and communication.
Head of Banking Cooperation Department, LianLian International
Ma Xiao joined LianLian in June 2021 and is responsible for domestic and international financial institution affairs. Prior to this, he worked at a well-known foreign bank, specialising in international payment settlement business. With over ten years of experience with financial services such as cash management for large foreign-invested enterprises in China, he has extensive knowledge and experience in international payment settlement products, services, compliance regulations, etc.
Chairman, TrustDecision; Co-founder and Partner, Tongdun Technology
Jackal has 30 years of working experience covering North America, Australia, Asia, and Europe. He is a seasoned technology and business executive, with previous experience including: Senior Engineer at IBM China/Hong Kong/Canada; Head of Technology Planning at Royal Bank of Canada; Chief Architect of Hong Kong Octopus Card System; Asia Regional Head of Operation at AXA insurance; President at EDIFY Asia, a JV between the US and China; Managing Director at Aspect Software for North Asia. He is an advisor and consultant at various business/technology transformation initiatives such as Citibank, HSBC, Standard Chartered, PingAn Insurance, China Construction Bank, and Pudong Development Bank.
China including the Ministry of Industry and Information Technology, National Development and Reform Committee. He was also VP of Asia Pacific at Threat Metrix, and co-founded Tongdun Technology.
Strategic Planning Expert, Strategic Planning Management Headquarters, Hundsun Technologies
At Hundsun Technologies, Zhichen is in charge of strategy planning and market insights. He possesses deep understanding of the digital transformation occurring in the insurance and banking industries, along with creative applications of financial technology. Previously, he led projects such as the non-trade finance blockchain platform of the Industrial and Commercial Bank China and the cross-border financial services platform of the State Administration of Foreign Exchange.
GM, Retail R&D Centre of Financial Technology Division; Co-President, Basic Retail Business Unit, PingAn Bank
Mr. Chu Liang served in various management positions at PingAn Group headquarters, PingAn Technology, and PingAn Bank. As Assistant General Manager and Chief Architect of PingAn Technology, he was responsible for product incubation and implementation in areas such as multimedia contact center, Internet, and mobile technology. He led major technology projects like PingAn Bank mobile banking, Orange Banking, and channel integration between the two banks.
He transferred to PingAn Bank in August 2016 and participated in the transformation of PingAn Bank's retail business as the chief technology leader. He set up the retail technology development team, fully implemented the agile development model and organisational governance, and led the team in technological exploration, research, and application innovations. He promoted the retail AI Banker project, systematically applying technologies like face recognition, OCR, big data, and AI to marketing, service, and risk business areas.
GM, Basic Middle Platform R&D Centre, Financial Technology Division, PingAn Bank
With over 20 years in banking IT, Mr. Liu has worked on large-scale projects and conceptual architectures like data services, big data governance, and AI banking applications. He has been deeply involved in the field of banking data governance and big data applications, contributing to CBRC's "big data governance of commercial banks" white paper.
In 2019, Mr. Liu joined PingAn Bank, leading the digital transformation of intelligent risk control and building a new digital risk control platform. His work earned awards from Gartner, The Asian Banker, and the People's Bank of China, and contributed to the Group's "Finance + Technology", "Finance + Ecology" and other strategic transformations.
Innovation Experiment Team Leader, Financial Technology Division, PingAn Bank
Zeng Yang is engaged in product innovation in AI, WEB3, domestic and international payments, etc. He joined PingAn in 2023 and is now deeply involved in PingAn Bank's fintech innovation business. He is committed to empowering the bank's digital transformation through technological and business innovation. Prior to joining PingAn, he worked for renowned enterprises such as China Minsheng Bank and ByteDance. He also co-founded and served as CTO of a UnionPay full-category filed aggregated payment service provider company. With 11 years of rich experience in financial technology product innovation and domestic and international market practice, he brings a wealth of knowledge to his role.
Chief Investment Officer, Micro Connect
Dr. Lin is Chief Investment Officer of Micro Connect. He and his team lead the firm’s efforts in investment portfolio construction, risk management, asset securitisation and fundraising.
Dr. Lin has decades of investment experience in both private and public markets. Prior to Micro Connect, Dr. Lin was one of the Founders and CEO of Goldstream Investment, a listed multi-asset and multi-strategy hedge fund platform. He managed quantitative investment portfolios and is a recipient of ‘Golden Bull’ Fund Manager Award. He was also a Partner and Managing Director of Hony Capital, a private equity firm in China. Dr. Lin also worked at China International Capital Corporation (CICC HK), Asian Development Bank (Manila) and the World Bank (Washington).
Executive Vice President, WeBank
Qiao became one of the primary members of WeBank's founding management team since April 2014 and has overseen the bank's strategic development and the incubation of innovative businesses, including wealth management, auto finance, SME loans, virtual credit cards, and international collaborations. He took on the position of Head of Financial Markets and Interbanking in 2020 and has been responsible for WeBank's financial asset management, FICC (Fixed Income, Currencies, and Commodities), asset securitisation, and interbank business ever since.
He's also been a Global Partner at McKinsey & Company in Chicago, Hong Kong, Taipei between 2005 and 2014, overseeing retail financial services in Asia, and serving as the regional leader for digital financial services, innovative businesses, and financial institution operations in Asia.
Senior Consulting Manager, Financial Technology Division, iFLYTEK
Pan Tao is currently in charge of AI financial solutions in the South China region. He has rich practical experience and profound insights into the application of artificial intelligence in the finance industry. He has led projects such as the intelligent services for the national hotline of China Merchants Bank and the intelligent precision marketing of Bank of China's Shenzhen branch.
Co-CTO, Linklogis
With over ten years of experience, Xu Yan is recognised as a remarkable pioneer in AI research and industrialization. He has received the Youth Science Fund, Postdoctoral Fund, and the Best Student Paper from the China Computer Federation's Artificial Intelligence Committee. One of his papers has been cited 700 times in total. Among his major achievements are the development of a personalised new recommendation system, a complicated network-based anti-fraud system, an AI Doc Check system, and a variety of other smart automation solutions.
Founding Partner, Jadestone Capital
Jay Huang is a founding partner at Jadestone Capital. Previously he was a managing director at Intel China. Prior to joining Intel, Jay was Vice President of Nortel Greater China and then Vice President of Nortel Asia.
Vice President, Enterprise Service, Alibaba Cloud
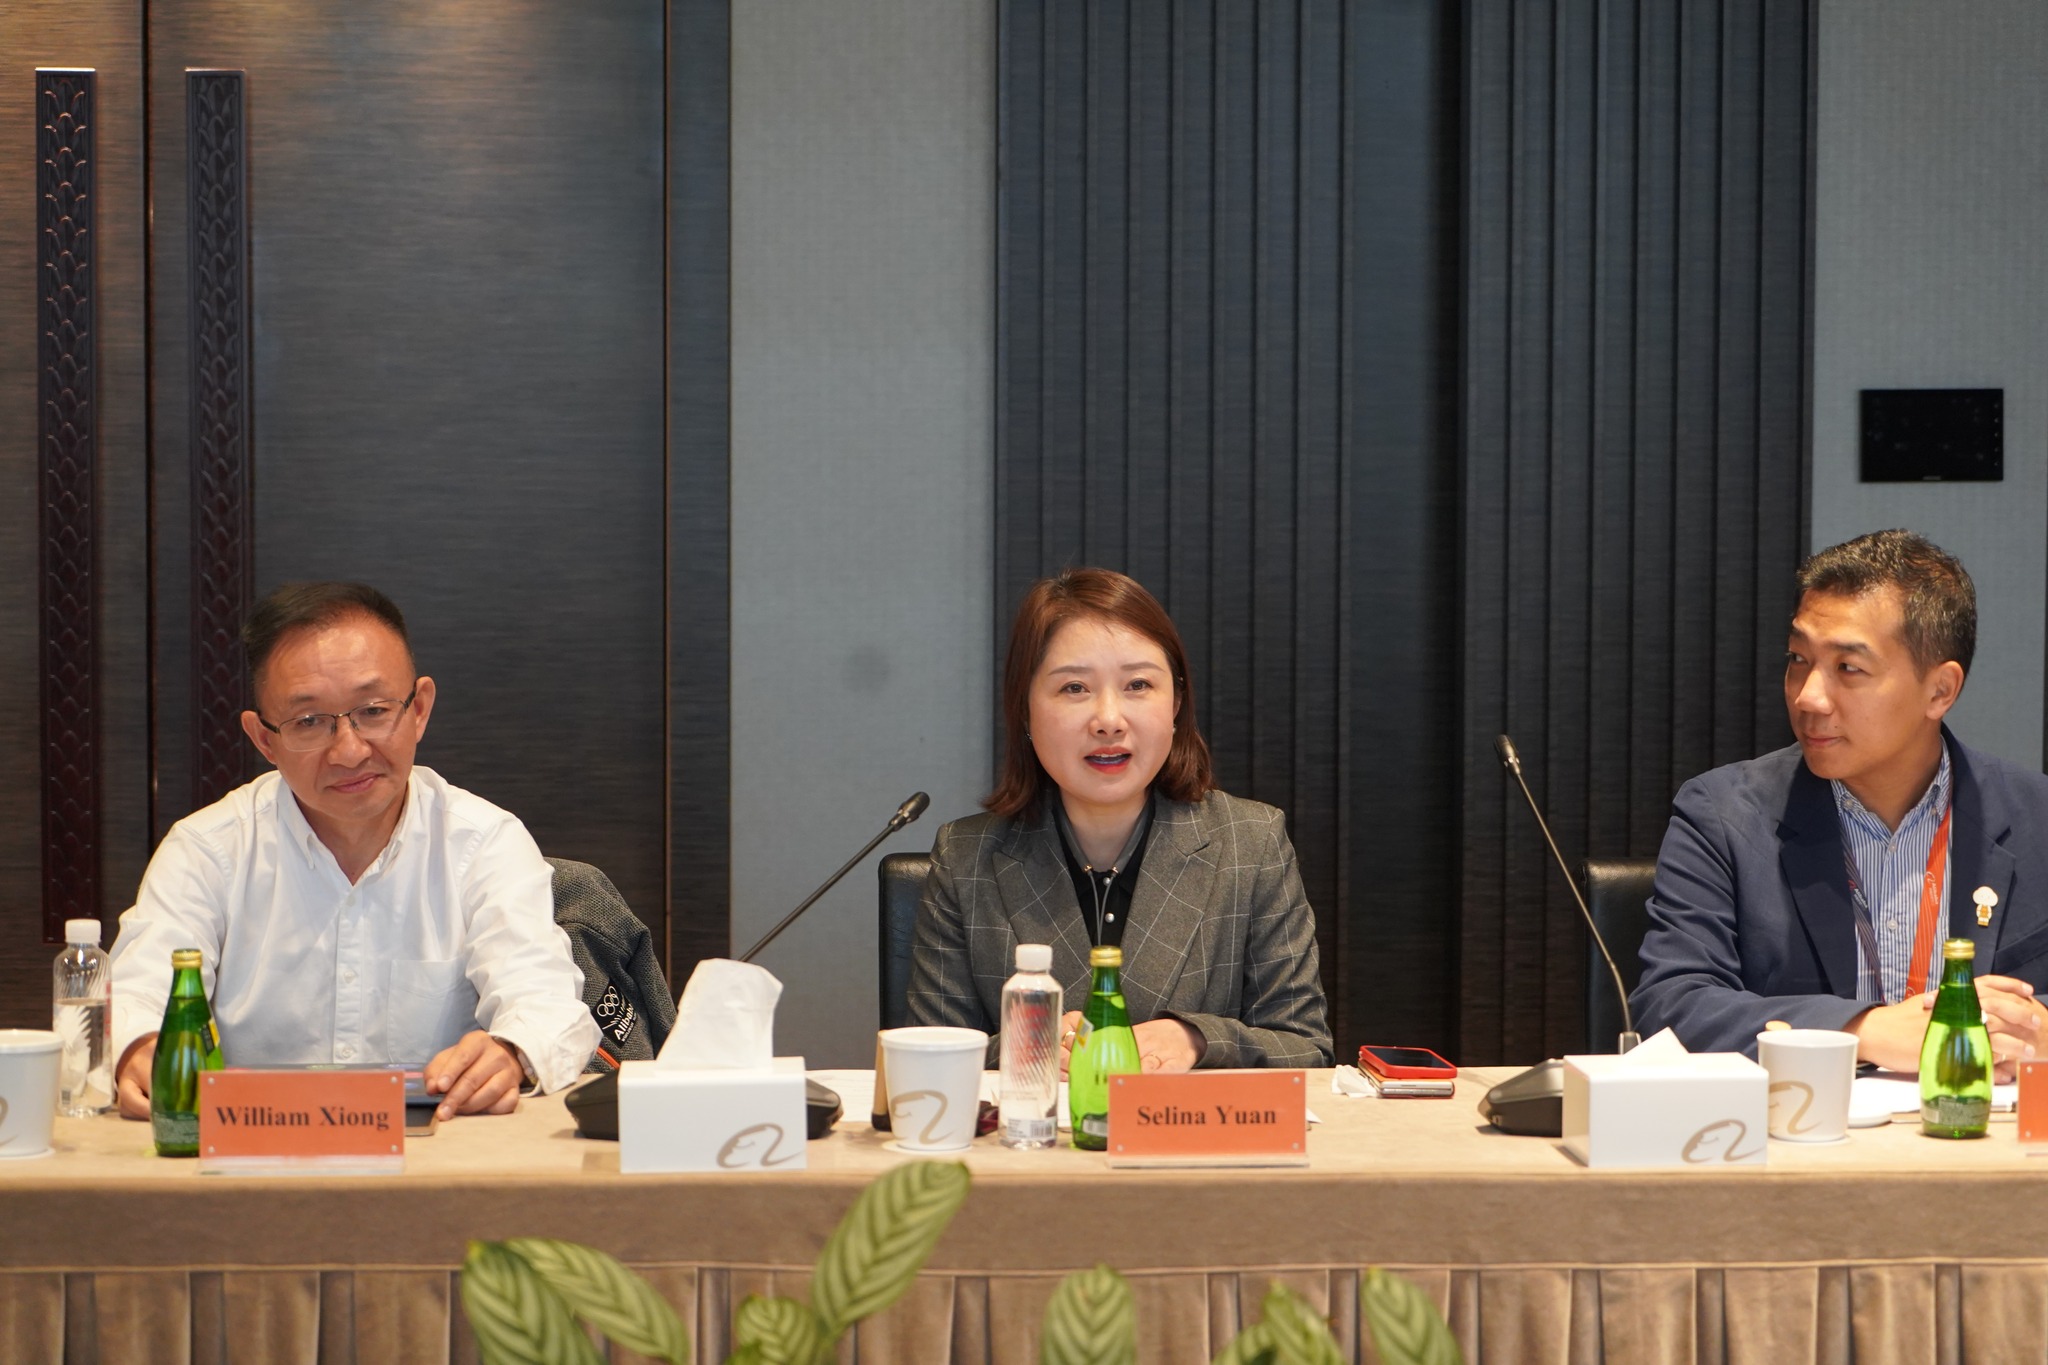
William XIONG is the Vice President of Alibaba Cloud, responsible for the Enterprise Service Cloud portfolio, which includes Energy Cloud, Sales & Procurement Cloud, Financial Cloud, Marketing Cloud, and the Enterprise Mobile Application Development platform. With a broad knowledge base in software and mobile development, e-wallets, insurance, data platforms, and carbon neutrality, William brings extensive expertise to the role.
Prior to Alibaba Cloud, William was the Senior Director of Technology at Ant Group, where he oversaw the development of international payment technology. Concurrently, he held a significant position as CTO of Worldfirst, leading the roll-out and partnership of e-wallets in numerous countries such as Paytm in India, Dana in Indonesia, TNG Digital in Malaysia, Kakaopay in Korea, Ascend Money in Thailand, Mynt in the Philippines, Easypesia in Pakistan, bKash in Bangladesh, among others. He and his team are committed to bringing inclusive, end to end, value driven cloud-based services and products to enterprises.
CTO, ZOLOZ (a wholly-owned subsidiary of Ant Group)
As CTO of ZOLOZ, a security technology-focused subsidiary of Ant Group, William Yao also holds a prominent role on the China Computer Federation Expert Committee on Big Data (CCF ECBD). Before this, he was the CTO of Ant Bank in Hong Kong and led the technical team for Alibaba Cloud’s CDN. A staunch advocate for open-source software, William Yao boasts over 15 years of expertise in the internet and fintech sectors.
Founder, TAB Global
Internationally renowned banking industry expert Emmanuel Daniel designed this programme for leaders entrusted with defining new frontiers in banking and responding to new technologies as they evolve. He is the author of "The Great Transition – The Personalization of Finance is Here" and the founder of TAB Global, which includes The Asian Banker, The Banking Academy, and TAB Insights amongst others. Emmanuel also advises leading banks in Asia and serves on government committees focused on the future of finance.
Chairman, The Banking Academy
Urs Bolt is a seasoned professional with over 35 years of experience in financial services, specialising in digital banking and wealth management. He is a global influencer and thought leader in fintech, wealthtech, digital wealth management, and digital assets. Bolt has a proven track record in developing digital platforms and leading strategic initiatives, including creating a B2B social business platform for wealth managers, digital investment platforms, prime services for high-net-worth clients, post-trade services for FX/OTC products, and business transformation projects. He helps financial service providers and tech companies refine business strategies, develop solutions, and build partnerships.
Bank Analyst and Former Executive Director at UBS
A Cambridge University PhD, Nick Dove became a bank analyst and executive director at UBS, where he advised bank management on strategy and equity issuance, as well as senior fund managers on investment strategy. His team was ranked the best European all-sector research team by fund managers. Since leaving UBS, Dove has advised governments, development agencies, and financial institutions on banking, private sector development, and the impact of regulation. He has written reports on sovereign wealth funds, infrastructure investment, and de-risking. He runs executive training courses on management development with John Howell. He is also a director of a $4bn London-based hedge fund with a concentration of investments in financial institutions, and a trustee of a charity focused on job creation in Sub-Saharan Africa.
Chairman and CEO of DBS Bank
Philippe Paillart was formerly vice chairman and CEO of DBS Bank and a pioneer in the retail banking industry in the Asia Pacific region, having served at senior management levels at Standard Chartered Bank and Citibank. Prior to his appointment with DBS, Paillart was Chairman, President, and CEO of Ford Motor Credit Company, and President of Ford Financial Services Group.
Independent Non-Executive Director, Recognise Bank, London
Honorary Professor, University of Kent Business School
Moorad Choudhry is an independent non-executive director at Recognise Bank Limited in London and an Honorary Professor at the University of Kent Business School. With over 35 years of experience in the City of London, he has served as Treasurer and Chair of the asset-liability committee (ALCO) at four different banks. Throughout his career, Prof. Choudhry has managed balance sheet ALM, including capital, liquidity, and market risk. More recently, as a board director, he has overseen the review and approval of the Internal Capital Adequacy Assessment Process (ICAAP), the Internal Liquidity Adequacy Assessment Process (ILAAP), and related ALM policies at two banks. Moorad is a Fellow of the Chartered Institute for Securities & Investment, the London Institute of Banking and Finance, the Global Association of Risk Professionals, and the Institute of Directors. He is also a Liveryman at The Worshipful Company of International Bankers.
Professor of Finance, Frank G. Zarb School of Business, Hofstra University,
New York
Anoop Rai is a Professor of Finance at the Frank G. Zarb School of Business at Hofstra University, New York, where he teaches corporate finance, international finance, and risk management. He is a partner at ProBanker Simulations, which develops training simulations for universities and corporate programs. With over 20 years of experience using simulations as a teaching tool, his research focuses on international finance, banking, and global regulation, with publications in major financial journals. Prof. Rai is Associate Editor of the Journal of Multinational Financial Management and co-author of two textbooks: Principles of Banking and Basics of International Business. He has lectured at several universities and conducted training seminars for financial institutions across Europe, Asia, and the Middle East.
Former Group Head, Digital Assets Strategy,
ClearBank
Jonny Fry led initiatives around blockchain and digital assets within the regulated banking environment at ClearBank. With over three decades of experience in financial services, Jonny is widely recognised as a thought leader in digital innovation. He is currently the CEO of TeamBlockchain, Chairman of Gemini Capital UK, and author of Digital Bytes, a weekly publication analysing blockchain developments. At ClearBank, he focused on integrating digital asset strategies to support institutional-grade infrastructure for next-generation financial services. In 2022, he was named CryptoAM’s “Influencer of the Year.
Corporate Affairs Director
OakNorth
Valentina Kristensen is part of OakNorth, one of the UK’s most prominent fintech success stories. Since joining the bank shortly after its inception, she has played a key role in shaping OakNorth’s strategic direction across stakeholder engagement, external affairs, and public policy. At OakNorth, Valentina is part of the executive team supporting the bank’s mission to reimagine SME lending through AI-driven credit intelligence and personalised banking solutions for growth-oriented businesses.
Head of Accounts
Greengage
Steve brings to the team a thorough understanding of retail banking garnered through 20 years working at Barclays Bank in the City of London. Having undertaken several leadership roles for Barclays Steve moved into relationship banking where he found a natural ability to deliver outstanding service on a human level.
Founder & CEO
Open Banking Excellence
Helen Child is the Founder and CEO of Open Banking Excellence (OBE), the world’s leading community of Open Banking and Open Finance pioneers. With a legacy of innovation rooted in her family’s 400-year history in banking, Helen’s journey includes founding the UK’s first e-Money Licence Issuer to be awarded licences by Mastercard and Visa. She has played a pivotal role in the development of the UK’s Open Banking ecosystem and has become a global ambassador for the movement, advising governments and regulators in emerging markets like Brazil and Saudi Arabia.

CEO, KAF Digital Bank
With over 25 years of experience in strategy, finance, banking, and innovation, Rafiza Ghazali currently serves as the CEO of KAF Digital Bank, where she is responsible for the development and operationalisation of the retail/consumer digital bank. She brings deep expertise in corporate finance, Islamic finance, and fintech to her leadership role.
Previously, she was the Group CEO of Cradle Fund, where she played a key role in transforming Malaysia’s early-stage funding and venture capital ecosystem. Her extensive C-suite experience spans across various sectors including consumer products and services, energy, property, and media—where she has contributed to enhancing performance, governance, and sustainability. Rafiza is a Chartered Accountant with the Australian Institute of Chartered Accountants. She also holds a Postgraduate Diploma in Strategy and Innovation from the University of Oxford and a BSc in Economics from the London School of Economics. She is passionate about creating meaningful impact through digital innovation in banking and advancing financial inclusion. She is also deeply committed to fostering a culture of collaboration, diversity, and excellence across her teams and stakeholders.

Head of Transaction Banking & Cash Management, Singapore and ASEAN Standard Chartered
With over 22 years of experience in transaction banking, treasury, and finance across Asia and the USA, Ankur Kanwar drives strategic growth and innovation in his dual leadership roles. As Head of Transaction Banking for Singapore and ASEAN, he oversees business growth and operational excellence in one of the region's most dynamic markets. In his global role as Head of Structured Solutions Development for Cash Management, he leads a team of experts in creating advanced cash management solutions for clients worldwide.
Ankur has helped large corporates optimise cash and treasury operations and spearheaded the adoption of transformative digital solutions to meet evolving industry needs. Before joining Standard Chartered, he held senior roles at JP Morgan Chase in Singapore and New York, leading transaction banking regulatory products and enhancing liquidity structures for corporate clients. His expertise in regulatory insights, treasury management, and balance sheet optimisation makes him a key influencer in transaction banking across ASEAN and beyond.

Group Head and Principal Economist, ASEAN+3 Macroeconomic Research Office (AMRO)
Allen Ng is Group Head and Principal Economist at the ASEAN+3 Macroeconomic Research Office (AMRO). He leads the Regional Surveillance group, which is responsible for the annual flagship ASEAN+3 Regional Economic Outlook and related updates.
He was previously the Chief Economist of Securities Commission Malaysia (SCM), where he was also a member of the International Organization of Securities Commissions’ Committee on Emerging Risks and a board member of the Institute for Capital Market Research Malaysia. Prior to SCM, Allen was Director of Research at Khazanah Research Institute, and before that he spent more than a decade in the Central Bank of Malaysia.

Managing Director, Regional Head Institutional Cash & Trade, APAC Deutsche Bank
Sebastien joined Deutsche Bank in 2010 and currently leads Institutional Cash & Trade for APAC, based in Singapore. He oversees cash and trade businesses for institutional clients across the region, supported by a team of 50. Previously, he headed Trade Finance Distribution for APAC and led the Distribution franchise for the Middle East & Africa. With experience spanning Europe, Russia & CIS, and MEA, he has managed syndications and trade finance across major markets. Before Deutsche Bank, he spent nine years at BNP Paribas, focusing on loan syndications in the oil, gas, and commodities sectors.

APAC CISO, Deutsche Bank Asset Management
Frankie Shuai is the APAC Chief Information Security Officer (CISO) at DWS, Deutsche Bank Asset Management, with over two decades of experience in Financial and IT industries. As a seasoned leader, he previously directed cyber and technology risk at UBS for Singapore, Australia, and New Zealand, and has held positions at Citibank, Microsoft, and HP. Frankie is renowned for bridging the gap between cybersecurity and business agendas, evidenced by his frequent speaking engagements at industry events. His commitment to digital transformation and innovation is underscored by a patent for next-generation wireless networking filed with the United States Patent and Trademark Office, where he serves as the sole inventor. In his current role at Deutsche Bank Asset Management, he leads regional Information Security, contributing significantly to the institution's cybersecurity resilience.

Seasoned CIO, CISO, and Award-Winning Technology Leader
David Gee is a distinguished former Global Head of Technology, Cyber, and Data Risk at Macquarie Group, celebrated for his transformative leadership across multiple industries and geographies. With over 25 years at the helm as CIO and CISO, including pivotal roles at HSBC Asia Pacific and MetLife, David has been instrumental in driving major digital transformations. He is notably recognized as the CIO of the Year 2014 for his strategic overhaul at Credit Union Australia, significantly enhancing their core and digital banking platforms. His latest book, The Aspiring CIO & CISO, published in July 2024, is a comprehensive guide for emerging leaders aiming to excel in top IT roles, offering strategies to develop leadership skills, build personal brands, and navigate executive challenges effectively.

Business Development Director, Global Fraud Solutions, GBG
Stephen Tjokro is a Business Development Director, Global Fraud Solutions at GBG. He has a keen interest in fraud management, cybersecurity, digital risk protection and enterprise software. With deep expertise in fraud management, he helps businesses navigate fraud risk challenges in an evolving digital landscape. Beyond his professional expertise, Stephen prioritises fitness and stays informed on emerging technology advancements, ensuring he remains at the forefront of innovation.
Chief Technology Officer, Lexin
Erwin Lu is the chief technology officer at Lexin, responsible for leading the company’s overall technology development. He has over 20 years of experience in technology R&D and management, having held senior leadership roles at major internet companies in both China and the U.S. Before joining Lexin in 2021, he was the chief information officer at Ping An Life Insurance. He also served as CTO at 51Talk and Sina Mobile, and as general manager of the advertising division at Sina Weibo. Lu began his career in 2003 as a software engineer at Microsoft’s Seattle headquarters and later worked at Facebook as a senior software engineer. He holds five U.S. technology patents.
Vice General Manager, Spark Enterprise Group, iFlytek
Su Bo is an AI solutions expert with extensive industry experience. As Vice General Manager of Spark Enterprise Group at iFlytek, he has led and participated in over 100 intelligent solution and large model projects for major Chinese financial institutions including ICBC, Bank of China, Agricultural Bank of China, PICC, and China Life Insurance, covering solution design and implementation.
Banking AI Research and Model Risk Leader
Lecturer, University of Hong Kong
Juergen Rahmel is the Artificial Intelligence Lead at the Chief Digital Office of HSBC Hong Kong and a Generative AI Lecturer at the University of Hong Kong. With over three decades of international experience, he specialises in artificial intelligence, machine learning and digital innovation in financial services. At HSBC, he has spearheaded AI research and development across areas such as biometrics, blockchain/DLT, big data, digital identity, and compliance, driving transformation across APAC. Beyond his corporate role, he advises technology firms and start-ups on AI-driven solutions in feature extraction, pattern recognition and data intelligence. Recognised as both a strategic thinker and transformation leader, Juergen bridges deep technical expertise with business insight to advance the integration of AI into financial ecosystems.
Executive Director, Bangkok Bank
Charamporn Jotikasthira is currently holding the position of Executive Director at Bangkok Bank Public Company Limited., Independent Director, Chairman, Risk Management Committee, and Member of Audit Committee at Minor International Public Company Limited., Independent Director, Chairman of Risk Management Committee, and Member of Audit Committee at Singha Estate Public Company Limited., and Independent Director and Chairman of Risk Management Committee at Osotspa Public Company Limited.
He has held former positions as the President & Chief Executive Officer at Thai Airways International Public Company Limited and The Stock Exchange of Thailand, Chief Information Officer at Siam Commercial Bank Public Company Limited., Chairman at Electronic Transactions Development Agency, Member the Financial Institutions Policy Committee (FIPC) at the Bank of Thailand., and a Director at Thai Institute of Directors Association.
He holds an MBA from Harvard University and an undergraduate degree in Electrical Engineering and Computer Science from Massachusetts Institute of Technology.
Head of Product, LINE BK
Kris is Head of Product at LINE BK, where he helps redefine how people connect with their money in the digital age. Bringing curiosity, creativity, and a human touch to the world of finance, Kris thrives on solving real-life problems with simple, delightful solutions. With a background in building customer-centric products and leading diverse teams, he enjoys turning big ideas into meaningful experiences that make finance feel approachable — and even a little fun. Kris believes that financial services should empower people, not intimidate them, and is passionate about designing with empathy and impact.
SVP, Head of Enterprise Risk and Infrastructure, Risk Management, CIMB Thai Bank
Dr Nongnuch Tantisantiwong is Senior Vice President and Head of Enterprise Risk and Infrastructure at CIMB Thai Bank. She leads key areas including credit risk modelling, data governance, system implementation, climate risk management and monitoring of risk appetite. She brings over 20 years of experience in financial system development, modelling, portfolio analytics and risk management. Before joining CIMB Thai, she held senior roles at Krungthai Bank, including SVP of Corporate Strategy and Head of Credit Risk Modelling and Analytics.
Earlier in her career, she served as Head of Financial System Policy Development at Thailand’s Ministry of Finance. She also spent over a decade in the UK, where she was a university lecturer and Programme Director in Risk and Finance and collaborated with the School of Electronics and Computer Science at the University of Southampton. She has published extensively on banking, investment, risk modelling, and sustainability and continues to contribute research to leading journals.
Vice Chairman & Group CISO, Kasikorn Business Technology Group (KBTG)
Chatchawat Asawarakwong is Group Chief Information Security Officer (Group CISO) at KASIKORNBANK and Vice Chairman of the Thailand Banking Sector CERT (TB-CERT). He brings over 20 years of experience in IT and cybersecurity management, with a deep focus on securing digital transformation in the banking sector. At KBTG, he oversees the bank’s enterprise-wide cybersecurity strategy, risk governance, and resilience initiatives, playing a key role in defending critical infrastructure against emerging threats. He also contributes to industry-wide collaboration and security policy development through his leadership role at TB-CERT.
Before joining KASIKORNBANK, Chatchawat served as Head of Information Security and Business Continuity Management at a regional bank in Thailand. His prior experience includes working as an IT security consultant with Big Four firms in both Thailand and the United States, advising major financial institutions on risk, compliance, and cyber defence. His extensive background combines hands-on technical expertise with strategic leadership across risk management, regulatory readiness, and security innovation in high-stakes financial environments.
Chief Digital & Technology Officer, Partner, & Advisor
Axel Winter is a highly experienced technology leader with strong hands-on experiences in the banking, retail and start-up worlds. He was previously Global Head of Enterprise Architecture & Technology Strategy for Standard Chartered Bank and had similar roles at GE Money and Cisco Systems. He has consulting experience at Accenture and Deloitte, and has recently founded a corporate start-up partnering with Grab and JD.Com. He is currently the Chief Digital Officer for a luxury mall operator and advises start-ups in asset tokenization and eCommerce. His expertise in technology infrastructure for banks and large businesses makes him a valuable contributor.
Risk Management & Regulatory Strategy Expert
Brian Lo is a seasoned risk professional with nearly 30 years of experience across global financial institutions. Based in Hong Kong and Singapore, he has led teams in managing market and liquidity risk, counterparty risk, and asset and liability management. His expertise encompasses quantitative modelling, risk governance, stress testing, and regulatory compliance. Brian has also played a critical role in developing internal risk models, driving strategic initiatives, and advising on cutting-edge risk solutions, including AI and machine learning applications. Throughout his career, he has served on multiple risk committees, providing strategic insights to senior management and boards, and has been instrumental in implementing Basel reforms and risk management innovations. Brian’s approach integrates deep technical knowledge with practical leadership, making him a valuable contributor to banking risk management education and practice.
Deputy Director and Research Fellow, CEIBS Lujiazui International Institute of Finance
Liu Gongrun is the deputy director and research fellow at the CEIBS Lujiazui International Institute of Finance. He also serves as secretary general of the CEIBS Lujiazui Finance 50 Forum (CLF50), executive member of the Shanghai Finance Society, specially appointed expert of the Shanghai Payment and Clearing Association, deputy director of the economic committee of the Xuhui District Political Consultative Conference, and deputy director of the financial technology special committee of the Shanghai Modern Service Industry Federation.
His research focuses on macroeconomic policy, financial center development, and emerging areas of finance. He has led dozens of major government advisory and commissioned research projects and has published five monographs, including Exploring Certainty.
Founder & CEO, Momentum Works
Li Jianggan is the founder and chief executive officer of Momentum Works, a Singapore-headquartered venture outfit that builds, advises, and invests in emerging market ventures. He previously served as managing director of Foodpanda Singapore, where he was appointed by investors to focus on sales and delivery operations. Earlier, he launched the Singapore operations of Easy Taxi under Rocket Internet, a Germany-based company that incubates, builds, and invests in internet ventures globally and grew it into the platform’s largest Asian market. He later oversaw operations across six Southeast Asian countries, driving regional expansion, product innovation, and strategic partnerships with Tencent, Huawei, VISA, and Microsoft. He also co-founded and successfully exited a licensed consumer fintech company in Southeast Asia. Li is the co-author of Seeing the Unseen: Behind Chinese Tech Giants’ Global Venturing, written with INSEAD Professor Chen Guoli, which examines the rise of Chinese internet firms overseas.
Vice President, Research and Strategy, University of International Business and Economics - Israel
John Gong currently is the vice president of research and strategy at University of International Business and Economics in Israel. He is also a professor, researcher and expert in the fields of finance, international trade, antitrust, patent dispute and competition policies. He serves as an expert consultant at the Ministry of Commerce’s Antitrust Bureau in China, and acted as the chief architect of the Bureau’s national competition database project. Meanwhile, he is serving as an academic affiliate with Global Economics Group, a leading global economics consulting firm based in the US. He is also the principal author for the China section of the policy position paper by the BRICS New World Bank’s steering committee during its foundation time. He is also a renowned op-ed columnist for several leading newspapers including the South China Morning Post, Global Times and China Global Television Network, on economic and political issues.
Executive Director & Board Member, German Chamber of Commerce in China - North China
Oliver Oehms serves as the chief representative of the Delegation of German Industry and Commerce in Beijing and is the executive director and a board member of the German Chamber of Commerce in China – North China. Prior to this, he held the position of CEO at the German Emirati Joint Council for Industry and Commerce (AHK), which encompassed five Gulf countries and Pakistan, and he also served as an ex officio delegate to Iraq. From 2016 onwards, Oehms led the German Chamber Abroad (AHK) in Riyadh, managing operations in Saudi Arabia, Bahrain, and Yemen. Earlier in his career, he worked with GIZ in Jakarta, where he contributed to the establishment of a new service unit at KADIN Indonesia. From 2003, he directed the foreign trade and trade fairs department of a regional German Chamber of Commerce and Industry. Oehms began his career at the German-African Business Association (Afrika-Verein e.V.), where he advanced to the role of Regional Manager for Western Africa.
Senior Director
Technology Risk Supervision Department, Bank of Thailand
Aurora is the Senior Director of the Technology Risk Supervision Department at the Bank of Thailand. She worked in payment policy and supervision for 7 years and more than 15 years in Technology risk policy and supervision, setting IT and payment regulatory and supervisory frameworks, guidelines, best practices, and collaborating with the industry and other stakeholders to build a trusted and secured banking community for IT and Cyber defenses.
Aurora earned her Master of Business Administration in Finance from Eastern Michigan University and a Bachelor of Science in Computer Science from Thammasat University.
Asia Representative
Bankers Association for Finance and Trade
T. S. Shankar has served as Asia Representative for the Bankers Association for Finance and Trade (BAFT) since August 2022, overseeing engagement and advocacy across the Asia-Pacific region. Based in Singapore, he brings over three decades of leadership in international transaction banking, with senior roles at Standard Chartered Bank—where he managed global payments, liquidity and trade finance initiatives including SWIFT GPI and blockchain pilots—and at Bank of America Merrill Lynch, where he built correspondent banking and trade finance operations in Southern Asia. Between 2019 and 2022, Shankar led Asia operations for the fintech firm Traydstream and served as Senior Principal at Infosys Consulting. He holds a BSc in Physics from Nowrosjee Wadia College and an MBA from the University of Pune, and regularly speaks at industry forums on payments innovation and trade digitization.
Chairman, The Banking Academy
Urs Bolt is a seasoned professional with over 35 years of expertise in wealth management, investment banking, and technology. He helps individuals achieve financial well-being and advises senior leaders in financial services and technology on refining business strategies, developing markets, and forging impactful partnerships. Recognised as a global thought leader in digital banking, WealthTech, and decentralised finance, Urs is an active speaker, author, and jury member for esteemed awards and panels. A passionate advocate for sustainable progress, he champions energy policies that balance economic growth and ecological preservation through scientific solutions.
CDO @Unique FinanceGPT, AI Leader, AI Governance, #1 Woman in Banking and Fintech 2024 by Handelsblatt, Secure GenAI for Financial Services: Data Protection, IT Security & AI Governance Expert
Sina is Chief Data Officer at Unique AG – a rising European startup providing a GenAI-driven platform called Unique.AI to better understand customers and build more meaningful client relationships. Unique.AI is a tailored solution for the financial industry that aims to increase productivity by automating manual workload through AI and ChatGPT solutions.
Sina is a proven GenAI and data transformation specialist for financial applications with over 20 years of experience. Before Unique AG, Sina led data strategy projects at Credit Suisse AG and worked as a consultant at Accenture AG. She lectures on GenAI, AI Governance, and Data Protection at top universities like HSG St. Gallen and HEC Paris, inspiring future tech leaders. Sina also mentors startups on GenAI applications and serves on the ISO expert council in Switzerland. She was recently honored with the “Women in Banking and Fintech 2024” award for her Thought Leadership on Data Protection and AI Governance for GenAI applications for Financial Services by Handelsblatt (#1 business newspaper in Germany). Sina holds a PhD in Financial Modeling from the University of St. Gallen (HSG, Switzerland) and a Diploma in Economics from the University of Mannheim (Germany).
Former Group Head, Digital Assets Strategy, ClearBank
Jonny Fry led initiatives around blockchain and digital assets within the regulated banking environment at ClearBank. With over three decades of experience in financial services, Jonny is widely recognised as a thought leader in digital innovation. He is currently the CEO of TeamBlockchain, Chairman of Gemini Capital UK, and author of Digital Bytes, a weekly publication analysing blockchain developments. At ClearBank, he focused on integrating digital asset strategies to support institutional-grade infrastructure for next-generation financial services. In 2022, he was named CryptoAM’s “Influencer of the Year.
Chief Technology Officer, NiftyOne
David Parsons is an accomplished technology executive with over 25 years of experience leading digital financial infrastructure initiatives across the US and Europe. As Chief Technology Officer at NiftyOne, he drives innovation, technology strategy, and platform development. His expertise spans go-to-market strategies, business development, and regulatory frameworks, underpinned by a strong track record of working with global technology providers, hardware manufacturers, and software developers. David’s strategic vision and hands-on leadership have consistently enabled the successful deployment of scalable, secure, and compliant digital solutions in the financial sector.
CEO and Founder, LenderLink
Christo Georgiev is a seasoned financial technology executive with a strong track record in driving business growth and operational excellence across Southeast Asia. He is the founder and CEO of LenderLink, a company focused on advancing credit and lending innovation.
From 2019 to 2024, Christo served as Group COO and Country Manager (Philippines) at FinScore, a leading alternative credit scoring company. Under his leadership, the firm achieved 100% year-on-year revenue growth, forged strategic partnerships with over 30 top-tier financial institutions, and significantly broadened its market footprint and data capabilities. He led initiatives that processed millions of alternative data points monthly, advancing financial inclusion for the underbanked and unbanked.
Christo played a key role in raising $1.9 million from investors, including UBX Ventures (UnionBank of the Philippines’ CVC arm), and co-led FinScore’s successful exit to CTOS Digital of Malaysia in 2023. Following the acquisition, he remained with the company through its transition before stepping down in 2024 to launch LenderLink. Since 2012, Christo has held leadership roles across Operations and Business Development in Southeast Asia, building a reputation for strategic impact and execution in emerging fintech markets.
First VP, Head of Consumer Banking Applications, BDO Unibank
Francis Ongpin-Lock Chiu is an award-winning technology executive with over 25 years of experience driving digital transformation, innovation, and operational excellence in financial services. As First Vice President and Head of Consumer Banking Applications at BDO Unibank, he leads initiatives that enhance customer experience, optimize operations and align technology strategies with business objectives.
Francis has successfully led large-scale teams and strategic initiatives, including reducing system vulnerabilities, integrating core banking solutions for revenue growth, and managing multimillion-dollar portfolios.
Chief Technology Officer, UBX
Pancho Reyna is the Chief Technology Officer at UBX. With nearly 20 years of experience, he has served as CEO of a data analytics company, Head of Software Engineering for an international low-latency stock exchange operator, and Founder and CEO of a tech solutions services company. His expertise spans software engineering, data analytics, and tech startups in telecoms, banking, big data, and finance.
Chief Operating Officer, PBCOM
John Howard D. Medina is the Chief Operating Officer of the Philippine Bank of Communications. He has over thirty years of experience driving innovation, change and transformation for financial services across several countries.
John is one of the pioneers in the process and technology transformation practice for financial services and helped change the Asia-Pacific operations of one of the largest multinational banks. He subsequently established a consulting firm in the United States, helping create new digital business initiatives for US financial institutions and fintechs.
Prior to joining PBCOM, John was the Head of Global Operations, Technology and Credit for the Philippine National Bank, where he worked for almost fifteen years. He was also the Integration Director, who oversaw the merger of PNB with Allied Banking Corporation. Mr. Medina also worked at Union Bank of the Philippines for five years where he conceptualized and implemented digital banking products and services.
Global AI and Digital Transformation Strategist
Jaspar Roos is a global thought leader in artificial intelligence and digital transformation, with extensive experience bridging technology, business strategy and innovation. As CEO of Limpid & Co and AI Evangelist at Leadingwith.AI, he drives the adoption of AI to help organisations modernise business models and scale digital innovation. He also serves as Head of Programme on AI, Change and Digital Transformation at Beeckestijn Business School, where he trains executives on AI applications, change leadership and future-proof strategies.
With a background spanning financial services, energy, construction and technology ecosystems, Roos specialises in leveraging AI, big data and automation to create new business opportunities and operational efficiencies. His work with corporates, regulators, and start-ups emphasises AI deployment, cloud-enabled transformation and data-driven innovation. In addition, he contributes to policy-shaping initiatives such as the European Commission’s OISP group, underscoring his role in aligning AI strategy with broader digital economy goals.
AI Policy and Financial Innovation Leader
Board Member, Africa Fintech Network
Tavonga Muchuchuti is a senior AI and digital transformation leader with experience advising financial institutions, regulators and technology ecosystems across Africa and internationally. He is the managing director of Xavier Africa, an AI development and advisory firm delivering high-impact AI solutions for financial services, public sector institutions, and regulated industries across multiple markets.
Beyond his executive role, Tavonga serves on the Board of the Africa Fintech Network, where he contributes to shaping continent-wide fintech strategy, infrastructure development and policy engagement with regulators, banks and industry bodies. He also chairs the Tech & Products Committee at the International Digital Economies Alliance (iDEA), working with global stakeholders across more than 70 countries to advance responsible technology adoption, digital infrastructure and inclusive innovation.
Tavonga works closely with central banks, financial regulators and financial institutions on the practical application of AI in areas such as risk monitoring, compliance, financial inclusion and data-driven decision-making. His work bridges strategy, regulation and execution, with a focus on scalable AI adoption in complex financial ecosystems. He is also a board member at Botswana Accountancy College, where he advises on AI curriculum and digital capability development for future finance leaders.
Chief Information Security Officer & Data Protection Officer, PNB
Roland V. Oscuro, First Senior Vice President, is the Chief Information Security Officer and in concurrent capacity the Data protection Officer of the Philippine National Bank (PNB). He is an ISACA Certified Information Security Manager (CISM) and an Electronics and Communication Engineer.
Roland V. Oscuro, First Senior Vice President, is the Chief Information Security Officer and, in concurrent capacity the Data protection Officer. Prior to his present position, Mr. Oscuro was hired as IT Consultant of the Bank on November 2, 2003. In May 2004, he was appointed as the Head of Network Management Division of Information Technology Group with the rank of First Vice President. He was the Operational Support System Group Manager of Multi-Media Telephony, Inc (Broadband Philippines) prior to joining PNB. He was also connected with various corporations such as Ediserve Corp. (Global Sources), Sterling Tobacco Corporation, Zero Datasoft (Al Bassam), Metal Industry Research and Development Center, and Pacific Office Machines, Inc.
Head of Solution Consulting, APAC, ACI Worldwide
Askari Brown is a payments veteran with more than 25 years of payments and financial services experience, he drives new client acquisitions while harnessing strategic partnerships to enhance solution deployment and activation for ACI clients. During his ACI career, now spanning nearly two decades, Askari covered multiple leadership roles across the enterprise, with an emphasis on consumer and wholesale banking software solutions.
Askari also spent four years as the VP of Global Multi-rail Payments Practice Lead at Mastercard, where he led a global advisory team driving multi-rail payment opportunities and projects that focused on real-time, account-to-account, and cross-border remittance payments.
Director III, ICT Department
Securities and Exchange Commission
Oliver Vinzons Chato is an IT professional with nearly three decades of experience in the Philippine IT industry. His skillset includes software and hardware support, mobile and web application development and architecture, IT programme management, and the application of frameworks and methodologies.
He has been part of the Ateneo DISCS faculty, specialising in computer networks and blockchain. Since March 2020, he has been with the Securities and Exchange Commission, and has served as Director of the Information and Communications Technology Department since February 2022. In this role, he supports the Commission En Banc in leading its digital transformation and IT modernisation efforts.
Chief Information Security Officer, GoTyme
Albert Dela Cruz is currently the Chief Information Security Officer (CISO) of GoTyme Bank. GoTyme Bank is a joint venture of Tyme, a multi-country digital banking group, with members of the Gokongwei Group, namely Robinsons Bank, Robinsons Land Corporation, and Robinsons Retail Holdings, Inc.
Abet is an established executive in Information Technology and the pioneer of the practice of Information Security in the Philippines. He contributed to information technology, security, and data privacy related policies as well as to agency rules and legislations for the Philippine Government including The eCommerce Act (RA8792)
Anti-Cybercrime Act (RA10175), Data Privacy Act (RA10173), The Supreme Court rules on Electronic Evidence and eNotary. He continuously provides technical assistance and advisory to various government agencies and non-profit organizations “Pro-Bono Público”, as a private citizen and as Co-Founder, and Director of the Philippine Computer Emergency Response Team Coordinating Center (PHCERT/CC).
He is also a director and co-founder of HIGH FIVE HOPE – a not-for-profit organization based in Seattle Washington, U.S.A. which helps to get Filipino street children off crime and substance abuse through the power of sports.
Principal Solutions Engineer, APAC, Mambu
Angelina Tjahjana is a seasoned banking and technology leader with over 17 years of experience in financial services solution consulting, technical engagement, development, and implementation across APAC, the Middle East, and Europe.
She is a Principal Solutions Engineer for APAC region at Mambu. Since joining Mambu in 2019, she has been instrumental in growing the company’s footprint, driving new market entry, and improving the product offerings. Her expertise includes business analysis, retail and islamic banking, cash supply chain management, digital transformation, and cloud based solution. She’s passionate about making secure and reliable financial services accessible to all.
Lead ASEAN Banking AWS
Michael Araneta is the lead for AWS Banking in Southeast Asia (ASEAN). He is tasked to grow the prominence of AWS in the C-suite of leading banks in the region, contributing to AWS business development and thought leadership efforts across the region. He also covers how fintechs will be part of the strategy of banks in new themes such as core banking, embedded finance, and Banking-as-a-Service.
Michael Araneta has over 20 years of experience in research and strategic advisory for financial institutions across the region. Immediately prior to joining AWS, Michael was head for IDC Financial Insights Asia/Pacific, leading IDC’s team of analysts covering fintechs, and leading banks and insurers in their digital transformation effort.
Lead ASEAN Banking AWS
Michael Araneta is the lead for AWS Banking in Southeast Asia (ASEAN). He is tasked to grow the prominence of AWS in the C-suite of leading banks in the region, contributing to AWS business development and thought leadership efforts across the region. He also covers how fintechs will be part of the strategy of banks in new themes such as core banking, embedded finance, and Banking-as-a-Service.
Michael Araneta has over 20 years of experience in research and strategic advisory for financial institutions across the region. Immediately prior to joining AWS, Michael was head for IDC Financial Insights Asia/Pacific, leading IDC’s team of analysts covering fintechs, and leading banks and insurers in their digital transformation effort.
Chief Technology Officer, OwnBank
Franco Nazareno is the Chief Technology Officer of OwnBank, currently steering the bank’s transition from a legacy core banking system to a modern digital platform. With over 15 years of experience in fintech, insurtech, and digital operations, Franco has led transformative technology initiatives across various high-growth industries. He specializes in system modernization, cloud architecture, and digital strategy execution.
CTO Citystate Savings
Jose Maria “Mayi” Valdes brings 44 years of experience in the IT industry, with expertise spanning infrastructure design, IT management, and digital transformation. He has led IT groups in four banking institutions, a sales and manufacturing company, and an independent ATM deployer, implementing core banking systems, loan management platforms, trade finance, treasury, and insurance applications.
Mayi has spearheaded the rollout of digital banking solutions for internet and mobile platforms, fostered collaborations with payment gateways and fintechs, and recently evaluated advanced cybersecurity tools, including SIEM systems, to establish a Managed Security Operations Center (MSOC) for Philippine Business Bank. He has also assessed fraud management, threat intelligence systems, and cloud versus on-premise infrastructures.
Fintech Executive | Board Advisor – Financial Services & Digital Transformation (Former President & CEO, UBX)
John Januszczak is a recognized leader in the fintech industry, known for his innovative vision and strategic expertise. As former CEO of UBX, UnionBank of the Philippines’ fintech spin-off, he spearheaded transformative initiatives that reshaped financial services through technology. With over two decades of experience, he has consistently driven growth, operational excellence, and customer-focused innovation.
Under his leadership, UBX launched groundbreaking products and services for diverse markets, fostering a culture of collaboration and inclusivity. He skillfully navigated complex regulatory landscapes, ensuring compliance while pushing fintech’s boundaries. Prior to UBX, Januszczak served as COO of Manulife Philippines, a leading multinational insurer.
Beyond corporate leadership, he actively engages in industry forums, sharing insights on finance and technology, and mentoring emerging talent. A strong advocate for diversity and inclusion, Januszczak remains a key voice shaping the future of fintech, championing sustainable growth and technological advancement.
Founder & CEO, Philippine Digital Assets Exchange
Nichel Gaba is the Founder and CEO of PDAX, the Philippines’ largest homegrown cryptocurrency exchange, licensed and regulated by the Bangko Sentral ng Pilipinas since 2018.
PDAX provides over 90 million Filipinos with secure access to digital assets—including crypto, stablecoins, and tokenized securities—and is at the forefront of the country’s push toward broader blockchain adoption. Under Nichel’s leadership, PDAX is driving innovation in digital remittances and pioneering the tokenization of traditional assets such as government bonds.
Before founding PDAX, Nichel held key roles in trust, investment management, and securities services at HSBC.
World Bank Consultant & Ambassador
EPAA, Currency Research, AI 2030
Rahul Bhargava is a globally recognised leader in financial services and payments, with over 22 years of experience driving innovation, digital transformation, and responsible AI adoption. He has led major initiatives across organisations like SWIFT, the World Bank Group, WEF, Accenture, FIS, and EPAA, focusing on digital money evolution, cross-border payments, CBDC interoperability, and emerging technologies.
Rahul has played a key role in launching next-generation payment systems, fostering interoperability, and advancing instant payments and open finance. He works closely with both public and private sectors on strategic programmes aligned with the G20 agenda.
Recently recognised as a “Responsible AI Leader” by AI2030 and awarded “Ambassador of the Year” by EPAA and AI2030, he is a frequent speaker at global events such as Sibos, Money 2020, and the Singapore Fintech Festival. He currently leads a global consulting portfolio, advising banks, fintechs, and governments on navigating the future of finance and payments.
Co-Founder, International Digital Economy Association
Amor Maclang has led cross-functional and cross-border collaborations among regional and national line agencies, industry leaders, academes, policymakers, and various stakeholders both from the private and public sectors. As the convenor of Digital Pilipinas, the largest private sector led movement for creating an innovation and a technology ecosystem in the Philippines, Amor continuously champions the mass uptake of blockchain, web 3.0, cryptocurrency, e-commerce, and fintech to raise the country’s innovation quotient.
Amor is currently one of the advisors of the Department of Finance, the Department of Trade and Industry, the Department of Science and Technology, the Department of Information and Communications Technology, and the Department of Health initiating transformational change in line with her mission to transform the country into diverse antifragile ecosystems.

Head of Transaction Banking Product, APAC SMBC
Atul Bhuchar is the Head of Product for Global Transaction Banking at SMBC Asia Pacific, leading product strategy, development, and commercialization to help businesses and financial institutions optimize working capital and strengthen supply chains. With expertise across TradFi, CeFi, and DeFi, he drives digital transformation in the transaction banking space.
Previously, Atul was Head of Product at Partior, a blockchain-based market infrastructure firm backed by Temasek, DBS, J.P. Morgan, and Standard Chartered. He also held senior roles at DBS, including Group Head of Payments and Head of Cash Management in India, and began his career at Citibank, later working with HSBC.

Director, Market Manager, International Payments Treasury Services APAC BNY
Raj Raman is the Market Manager for International Payments Product for Treasury Services in Asia Pacific (APAC). Raj drives the Technical Sales, Solutioning and Market Intelligence across Cross-Border Payments including USD Clearing, Multi-Currency and FX payments. Raj focuses on understanding the unique requirements of clients in the region to drive Product Adoption and Commercialization, while also promoting Thought Leadership and obtaining insights on market trends. Raj also keenly tracks market behavior around Pricing, Real-time Payments, New Payment Service Providers with the aim to enhance the overall end-to-end experience in the payment lifecycle. Raj brings over 20 years of experience in the cross-border payments space with various leadership roles across Technical Sales, Customer Experience, Complex Implementations, Analytics and Operations during his time previously at Wells Fargo and American Express Bank.

Senior Executive Vice President Kotak Mahindra Bank
Amit Kumar is currently leading the cash management business at Kotak Mahindra Bank, overseeing its core verticals including product, liquidity, sales, and implementation. With 17 years at the bank, he has played a pivotal role in developing important product and technology stacks, driving significant advancements in these areas. Amit, a member of the wholesale leadership group at Kotak, is responsible for driving the liability strategy for enterprise customers, integrating the same with technology and product solutions. Under his leadership, the bank has been continuously awarded as the best cash management bank.

Advisor, Transaction Finance Awards, The Asian Banker; Seasoned Financial Services Industry Leader and Board Director
Bill Chua serves as Independent Director on the boards of Citibank Singapore, Newcastle Australia Institute of Higher Education, IES-INCA, United Hampshire US REIT Management, Sunseap Group, and Boardroom Executive Services. With 34 years of distinguished experience in the financial services sector, including leadership roles at UOB, Bill brings extensive expertise to his positions. He is recognized for his contributions to finance, education, and social sectors, having chaired operations sub-committees in banking and served on various advisory and investment committees. Bill was honored with the Public Service Star by the Singapore Government for his outstanding contributions to the nation. Former board appointments include Singapore Technologies Electronics, Jurong International, Clearing and Payments Services, DSO National Laboratories, Defence Science & Technology Agency, Singapore Technologies Kinetics, and CLS AG.

MD, Head of Global Transaction Banking for Asia Pacific
Mizuho Bank
With over 25 years of international banking experience, he has led the expansion and digital transformation of transaction banking across the region. Prior to Mizuho, he held senior leadership roles at Standard Chartered Bank and ABN AMRO, including Global Head of Working Capital and Regional Head of Transaction Banking for ASEAN & South Asia. Known for his expertise in digital ecosystems and innovation, Ashutosh has been recognized as Transaction Finance Leader of the Year at The Asian Banker Awards 2024. He currently serves as Co-Chair of the Asia Council at BAFT and is a Board Member, with previous roles including Chair of the Global Trade Industry Council and advisor to the ICC Banking Commission.

Independent Non-Executive Director, Alliance Bank Malaysia
Lum Piew is an Independent Non-Executive Director at Alliance Bank Malaysia, bringing extensive experience in banking, risk management, and corporate governance. With a strong background in financial services, regulatory compliance, and strategic leadership, Lum Piew has played a pivotal role in shaping the bank’s governance framework and operational resilience. His expertise spans across risk assessment, financial strategy, and digital transformation, ensuring the bank remains agile in an evolving financial landscape. As a thought leader in the industry, he actively contributes to discussions on cybersecurity, fintech innovation, and financial inclusion, helping to drive sustainable growth and customer-centric banking solutions.

Department Head of Wholesale Digital Channel
PT Bank Negara Indonesia (Persero) Tbk
Rahmananda is a seasoned banking executive with over 15 years of experience in digital transformation, payment innovation, and embedded finance. At BNI, he leads wholesale digital initiatives that integrate banking services into diverse digital ecosystems to promote financial inclusion and sustainable growth.
Previously, he held leadership roles at HSBC, focusing on global payments and treasury modernization, and began his career at Commonwealth Bank and T N Information Systems in Bangkok, contributing to digital banking and tech integration. He is known for driving API-led innovation and forging partnerships that support the shift toward open banking and embedded financial services.
Co-founder and Group CEO of Funding Societies | Modalku
Kelvin Teo is the co-founder and Group CEO of Funding Societies | Modalku. He has been a key member of the Singapore FinTech Association’s Digital Finance Subcomm since 2018 and recently named by the Association as among the Top 12 Fintech Leaders in Singapore in 2020. As one of the Top 200 FinTech Influencers in Asia, Teo has spoken at major conferences such as LendIt Shanghai, Boao Hainan and Money20/20. He has also been featured on Bloomberg, BBC and Business Times. Prior to this, Teo served as a consulting professional at KKR, McKinsey and Accenture.
Group Head and Principal Economist, ASEAN+3 Macroeconomic Research Office (AMRO)
Allen Ng is Group Head and Principal Economist at the ASEAN+3 Macroeconomic Research Office (AMRO). He leads the Regional Surveillance group, which is responsible for the annual flagship ASEAN+3 Regional Economic Outlook and related updates.
He was previously the Chief Economist of Securities Commission Malaysia (SCM), where he was also a member of the International Organization of Securities Commissions’ Committee on Emerging Risks and a board member of the Institute for Capital Market Research Malaysia. Prior to SCM, Allen was Director of Research at Khazanah Research Institute, and before that he spent more than a decade in the Central Bank of Malaysia.
Group Head and Principal Economist, ASEAN+3 Macroeconomic Research Office (AMRO)
With over 22 years of experience in transaction banking, treasury, and finance across Asia and the USA, Ankur Kanwar drives strategic growth and innovation in his dual leadership roles. As Head of Transaction Banking for Singapore and ASEAN, he oversees business growth and operational excellence in one of the region's most dynamic markets. In his global role as Head of Structured Solutions Development for Cash Management, he leads a team of experts in creating advanced cash management solutions for clients worldwide.
Ankur has helped large corporates optimise cash and treasury operations and spearheaded the adoption of transformative digital solutions to meet evolving industry needs. Before joining Standard Chartered, he held senior roles at JP Morgan Chase in Singapore and New York, leading transaction banking regulatory products and enhancing liquidity structures for corporate clients. His expertise in regulatory insights, treasury management, and balance sheet optimisation makes him a key influencer in transaction banking across ASEAN and beyond.
Managing Director, Regional Head Institutional Cash & Trade, APAC Deutsche Bank
Sebastien joined Deutsche Bank in 2010 and currently leads Institutional Cash & Trade for APAC, based in Singapore. He oversees cash and trade businesses for institutional clients across the region, supported by a team of 50. Previously, he headed Trade Finance Distribution for APAC and led the Distribution franchise for the Middle East & Africa. With experience spanning Europe, Russia & CIS, and MEA, he has managed syndications and trade finance across major markets. Before Deutsche Bank, he spent nine years at BNP Paribas, focusing on loan syndications in the oil, gas, and commodities sectors.
Director & Executive Officer, SBI Investment
Tomoyuki Nii is the Director and Executive Officer at SBI Investment Co. Ltd, where he plays a pivotal role in investing in fintech companies globally and facilitating their entry into Japan and Asia. He is responsible for establishing joint ventures between SBI Group and portfolio companies to drive growth and innovation. Mr. Nii is also the co-founder of ARUHI (formerly known as Good Loan Co., Ltd. and later SBI Mortgage Co., Ltd.), which was listed on the Tokyo Stock Exchange in December 2017. Under his leadership, the company grew to 200 billion yen in mortgage assets in just six years, creating Japan's first fixed-rate mortgage product and pioneering unique insurance products.
Head of Quantum Adoption and Impact, Pasqal
Based in Tokyo, Jean-Charles Cabelguen, PhD, is Head of Quantum Adoption and Impact at Pasqal, a quantum computing company using neutral atom technology for real-world applications. With 15+ years of experience in research, M&A, and international business development, he drives deep tech companies from lab to market. His work bridges quantum technology with practical industry adoption, positioning quantum computing as a catalyst for next-generation breakthroughs across industries.

Executive Director,Head of Trade Product Management, Group Transaction Banking United Overseas Bank
With more than 30 years’ experience in the banking industrial, Joseph has in-depth product knowledge of Supply Chain Solutions for both Trade Finance and Cash Management. Before joining United Overseas Bank, he was the Regional Head of Trade and Supply Chain Solutioning of Asia Pacific of Bank of America Merrill Lynch after he run the Regional Corporate Trade Product Management team. Prior to that, he worked in Royal Bank of Scotland deputizing the Global Transaction Services Hong Kong country head in managing the Cash and Trade business, and in BNP Paribas and Citi.

Regional Head of Transaction Bank Product, APAC MUFG
Doug is the Head of TB Product for MUFG in APAC. In this role he is responsible for the product development and product management of all Cash Management and Trade & Supply Chain Finance solutions in APAC. He is a seasoned Transaction Banker with 20+ years of working experience in Cash & Trade, covering both Sales & Product. He initially joined MUFG in Sydney in Jan 2017, as the Head of Sales for Trade & Supply Chain Finance business for Australia and New Zealand, before moving to Singapore to head up the Cash Product team for APAC, looking after Payments, Collections, Channels and Liquidity products.
Vice President of Data, Payments, GoTo
Dr. David Duan is the Vice President of Data, Payments at GoTo Group, where he leads both data science (ML & AI) and advanced analytics. He is a strategic data leader with over 15 years of experience helping organisations build and scale data and data science capabilities — from setting up functions from scratch, to defining and executing data strategy, embedding data science into core business processes, and leveraging ML and AI to drive product innovation and growth.
Consulting Professor, Design Group, Stanford University
Barry Katz has authored eight books, including "Change By Design" with Tim Brown (Harper Collins, 2009/2019), which explores design thinking as a business strategy; "NONOBJECT" with Branko Lukic (MIT, 2010), a conceptual exploration of "the space between person and product;" "Make it New: The History of Silicon Valley Design," translated into Japanese, Chinese, Korean, and Spanish; and "Healthcare by Design" (University of Toronto Press). He is currently working on his new book, "The Architecture of Information: Structure and Symbol for the Age of Data." His writings on design as a strategy for innovation have been featured in numerous academic, professional, and popular journals. Additionally, Katz serves as a Professor of Industrial and Interaction Design at the California College of the Arts and is a Fellow at IDEO, Inc., a global design and innovation consultancy.
Principal, Global Capital Markets
Shawn Flynn brings a wealth of experience as a seasoned mid-market investment banker. Having established himself as a successful business owner in Beijing, China, Flynn returned to Silicon Valley to immerse himself in the dynamic startup ecosystem. His roles have been diverse, ranging from Head of Incubation for an AI and blockchain-focused incubator to President of the second oldest Angel group in the Valley. With an extensive background spanning various business stages and sectors, Flynn currently holds the position of Principal at Global Capital Markets, a premier middle-market investment bank. This bank specializes in services such as mergers and acquisitions, growth capital raising, and secondaries. Flynn's global perspective is further enriched by his proficiency in Mandarin and Spanish, languages he acquired during his nearly 8 years of living abroad.
Principal, Global Capital Markets
Bill Barry stands out as an exceptional GTM (Go-To-Market) leader in the technology sector, boasting a proven track record of driving revenue growth for both established tech giants and high-potential startups. His unwavering pursuit of excellence, coupled with his talent for uniting diverse teams, has yielded staggering triple-digit growth trajectories and successful exits. By harnessing cutting-edge analytics and automating processes, Bill has earned a reputation as a revered advisor and mentor, renowned for consistently delivering exceptional results with an upbeat tempo.
With his robust technical background, strategic acumen, and remarkable interpersonal skills, Barry emerges as the top choice for businesses aiming to turbocharge their go-to-market capabilities and cultivate revenue engines. His profound grasp of the market landscape, combined with his ability to engineer and implement highly effective processes and systems, has established a pattern of unwavering success throughout his career.
Head Investor Relations, IgniteGTM
With a career spanning over 25 years as a registered investment banker and strategic consultant, Harold Graham is motivated by his commitment to supporting high-potential founders and connecting them with the most suitable capital partners. His expertise encompasses various industries, including technology, healthcare, and finance. Graham possesses a distinctive approach to fundraising that involves aligning the individual mission and goals of each startup. He understands that the success of fundraising extends beyond mere capital infusion; it involves a trifecta of strategic mapping, precise execution, and the cultivation of enduring alliances with investors. Throughout the intricate journey of fundraising, Graham expertly guides startups, helping them navigate the complexities, and securing the necessary resources to fuel their growth and innovation.
Co-Founder and CEO, Platina
Drawing from 25 years of industry experience in the telecommunications sector, Mark Yin has held esteemed leadership positions at renowned companies including Infinera, Ciena/Lightera Networks, Cisco, and Stratacom. Before co-founding Platina, Yin operated his independent consulting firm based in Asia, specializing in shaping strategies and investment directions for local Original Design Manufacturers (ODMs). Notably, he played a pivotal role as the inaugural VP of Marketing at Infinera (NASDAQ: INFN), a global pioneer in optical networking systems. During this tenure, he was instrumental in defining both current and future product lines, successfully launching the company, and subsequently establishing its influential presence in the Asian market.
Founder & CEO, knomee
Marla is a fintech founder, keynote speaker, and former executive at traditional wealth and asset management firms and leading transformational fintech providers. She led operational partnerships at BlackRock and J.P. Morgan quantified in the billions of dollars before leaping into fintech to improve customer experiences. She has built and scaled integration, channel, and corporate development partnerships at high growth fintech companies including Carta, Jemstep, Xignite, and Lending Club, innovating in the areas of private equity, digital advice, financial market data, and fixed income. She has experience as a client, a vendor, and a partner leading digital transformation in banking and capital markets, and as a change agent driving diversity and inclusion. She founded two women’s networks and speaks frequently on topics related to the evolution of financial services to broader audiences. In 2020, she was selected as a Silicon Valley Business Journal Woman of Influence, and was recognized in 2021 as a Woman in Wealth Tech to Watch.
Director of Business Development, BLAM Retail
Régine David's diverse expertise spans strategic partnerships in venture capital, finance, tech, art, non-profit, public, and private sectors. Prior to BLAM Retail, she directed business development at on-demand financial services firms, focusing on FinOps for private and public sectors. Her role emphasized revenue growth, retention, partnerships, and strategic branding. Régine also consults for startups on strategic partnerships, brand strategy, and business development. With a finance background, she built partnerships with advisors, founders, investors, and cohorts in the venture capital and tech ecosystem, offering guidance on internal and external business development.
Co-Founder/ Chief Digital Officer/ CTO, Iterate.ai
Brian Sathianathan’s career kicked off at Apple, initially chosen for his prowess in software development and encryption. During his 6-year tenure, he spearheaded iPhone and Intel Mac endeavors within the discreet New Product Introductions (Secret Products) Group. His key teams crafted the security and activation framework for the inaugural iPhone, resulting in his patent achievements. Subsequently, after an 8-year association, Brian departed Apple to establish Avot Media, which developed a video transcoding software used by major entities like Warner Bros. This venture culminated in its acquisition by Smith Micro [NASDAQ: SMSI]. At Smith, Brian ascended to head of the video division, steering strategy, vision, and integration.
Post his roles at Avot and Smith, Brian assumed a position on the seed-stage investment squad at Turner Media. Here, he scouted startups in Social, Consumer, Advertising, and Recommendation sectors, participating in 13 investments and a key acquisition (BleacherReport) across two years. Remarkably, two of his backed startups were subsequently acquired, including one by Apple.
Currently, Brian serves as Co-Founder and Chief Technology/Digital Officer at Iterate.ai, an innovation ecosystem initiated in 2013. Revered companies such as Ulta Beauty, The Pampered Chef, Driven Brands, and Circle K harness the "intelligent low-code" capabilities, a concept devised and patented by Brian and his team. This innovation, known as Interplay, significantly expedites and streamlines digital and AI-driven innovation. Notably frugal and highly efficient in capital usage, Iterate's revenues surged by 287% between 2017 and 2020.
CEO & Founder, LinkSV.com
Bob Karr is the CEO/Founder of Link Silicon Valley (LinkSV.com). He has been an active angel investor, an advisor to emerging internet companies, and a co-founder of the Angels Breakfast Club. Bob retired from a 30-year career in the corporate liability insurance business, during which he spent 15 years as a Partner at Dinner Levison Company and another 15 years as Senior Vice President of the Sedgwick Group. In these roles, he spearheaded business development and client services, exclusively focused on emerging and pre-IPO companies in Silicon Valley. Many of his emerging clients have transitioned into successful IPOs.
COO & Co-founder
A three-time entrepreneur with twenty plus years of business development, sales and marketing, Dawn currently leads day-to-day operations and product vision for Link Silicon Valley. She joined Bob in 2016 and led a total rebuild and relaunch of the website and SaaS offerings. Dawn started her career selling system software to Fortune 5000 firms and OEMs as chief rainmaker in her first company and went on to build a nationwide network of VARs and developers that doubled annual sales 3 years in a row. Dawn earned a BA in Economics at the State University of New York at Buffalo. She and her family now live on the San Mateo Coast.
Senior Managing Director, Newmark
Sherry Gubera is the senior managing director at the San Jose office, specializing in tenant representation for Silicon Valley tech companies. With vast industry experience, she optimizes facility acquisitions, dispositions, and lease restructures for startups and Fortune 1000 firms. Alongside her seasoned corporate real estate team, Sherry prioritizes lasting relationships and top-tier customer service. She's a trailblazer, holding Silicon Valley's first Leadership in Energy & Environmental Design (LEED) accreditation. Sherry authored Newmark's Green Handbook, a comprehensive guide for real estate professionals navigating green initiatives. At Newmark, she's completed 450+ assignments, advising tech, life science, and cleantech companies across 14.8 million square feet in lease and sale transactions.
Senior Managing Director, Newmark
Adam Green, Senior Managing Director at Newmark, joined in 2018 within the EMEA consulting practice of the Global Corporate Services division. He later moved to the global consulting team in 2020. With over 13 years of experience, Adam specializes in Integrated Workplace Services. His focus areas include workplace experience and planning, workplace technology solutions, outsourced service delivery, and facilities management. Adam excels in workplace strategy, change management, real estate consulting, technology-enabled workplace solutions, IoT, and program management. His leadership extends to vendor management and overseeing large teams.
Partner, Haynes and Boone
Roger Royse serves as a partner at Haynes and Boone, LLP's Palo Alto office, specializing in corporate and securities law, tax, and mergers and acquisitions. He provides counsel to a wide array of companies, spanning from nascent tech startups to publicly traded multinationals across various sectors. With the distinction of being a Fellow of the American College of Tax Counsel and a former chair of multiple committees within the American Bar Association Sections of Business Law and Taxation, Roger's legal expertise is highly regarded.
Furthermore, Roger's educational contributions extend beyond his legal practice. He has served as an instructor or professor for legal, tax, and business subjects at the Center for International Studies in Salzburg, Austria, Golden Gate University School of Law, and Stanford Continuing Studies. Nationally recognized as an authority in agtech (agricultural technology), Roger illuminates the legal landscape for companies operating in this domain.
Roger is the author of "10,000 Startups: Legal Strategies for Startup Success" and "Dead on Arrival: How to Avoid the Legal Mistakes That Could Kill Your Startup." His insights have garnered coverage in influential publications such as the Wall Street Journal, Forbes, Fox Business, Chicago Tribune, Tax Notes, Inc. Magazine, and many others.
SVP, Group Director, Innovation and Venture Banking Group, Flagstar Bank
Calina Thompson is the group director and senior vice president with the Innovation and Venture Banking Group at Flagstar Bank. She has over 18 years of experience working with Private Clients, entrepreneurs with a focus on startup, innovation, venture capital, and privately held businesses. Thompson also has expertise in the non-profit and private residential lending space. Prior to Flagstar, she was the senior relationship manager with First Republic Bank for 10 years.
CEO & GP, Portola Valley Partners
John Majeski brings a wealth of expertise encompassing startups, turnarounds, and major IT companies. Notably, he co-founded and played key roles in the success of 3 startups, all of which achieved successful exits. During his tenure at HP, he orchestrated the seamless integration of a company and fulfilled the role of CTO. At Dell, serving as VP/GM, Majeski not only successfully integrated a $1 billion acquisition but also remarkably propelled revenue growth from $400 million to $2.3 billion in a span of 3 years. During his time with Lenovo, he initiated and managed a global business endeavor aimed at acquiring technology, pivotal in steering Lenovo's transition from hardware to software and solutions. Majeski's leadership spans product, engineering, sales, and M&A domains.
Chair and Founder, RoseRyan Group
Kathy Ryan, Chair and Founder of RoseRyan Group, drives the firm's mission, strategy, and investments since co-founding it in 1993. She pioneered a flexible work-life balance model, now embraced by over 100 professionals at RoseRyan. After 26 years at the helm, Kathy appointed David Roberson as CEO in 2020, charting the firm's growth into a new era.
Kathy, known for her CEO and CFO experience with 50+ Silicon Valley startups, innovatively combined flexible work arrangements and a values-based culture at RoseRyan. She launched ventures like Bizinta, offering practice management software, and co-founded Kukuza Associates in 2019, specializing in cannabis accounting and finance.
Her leadership insights are sought after by industry and regional publications. The San Francisco Business Times recognized her as an influential woman in Bay Area business in 2015. Kathy appeared twice on Accounting Today's top 10 leaders list, known as the Managing Partner Elite. In 2012, the San Jose/Silicon Valley Business Journal named her one of the most influential women in Silicon Valley.
Enterprise Account Manager, Digital Realty (Silicon Valley Data Center)
Ray Ko has more than 18 years of experience in the data center and telecom space. Currently, he is assisting customers with best practices used in a data center to achieve digital transformation and optimal performance to meet their business demands globally.
CEO, HIA Technologies
Vacit Arat, CEO of HIA Technologies, is a seasoned serial entrepreneur with 25+ years of experience in operations and business development. Throughout his career, he has been at the forefront of pioneering new technologies, establishing viable businesses, and generating intellectual property (holding 22 US patents). His current venture, HIA Technologies, is the visionary force behind AIVIO™, an innovative digital assistant user interface revolutionizing healthcare communication.
AIVIO™ transforms the patient-provider dynamic beyond the confines of traditional office visits. This groundbreaking technology empowers healthcare providers with interactive digital representatives, enabling them to engage in sophisticated and empathetic conversations with patients. AIVIOs educate patients, address their inquiries about their condition, gather information through strategic questioning, and provide comprehensive interaction reports. The result: improved patient outcomes, enhanced communication, and cost savings.
CEO, Aggregage
Robert Flynn boasts a quarter-century legacy constructing and steering growth companies across internet and traditional media domains. He played a pivotal role in launching and overseeing Liquid Audio, a trailblazing venture that introduced a comprehensive software platform for lawful digital music distribution and commerce on the internet. His most recent endeavor involved being CEO and Co-Founder of Modern Feed & Supply, Inc., later rebranded as Clicker, ultimately acquired by CBS Interactive. In the interim, Flynn helmed Zetools, a pioneering software firm providing enterprise-grade solutions for IP video formatting, management, and distribution across all IP-based platforms through streamlined publishing. During his Zetools tenure, the company secured two Emmy Awards, and Flynn and his team earned recognition on Hollywood Reporter's Digital 50 list.
Director, Corporate Partnerships, Plug and Play
Allen Shi is a versatile professional excelling in corporate innovation and venture capital. Based in California, he's a driving force in cultivating strategic partnerships between corporations and emerging startups. Since February 2023, Allen has been pivotal at Plug and Play Tech Center, where he adeptly fosters alliances for mutual growth.
His previous role as Chief Revenue Officer at Brix Labs, an AI-driven engineering team management platform, underscores his adeptness in aligning technology with business goals. Prior roles, like Vice President at FTD Solutions LLC, showcased his proficiency in semiconductor facility systems and optimization. While serving as Chief Revenue Officer at LivNao, he demonstrated his commitment to mental health tech, despite the challenges the company faced.
Allen's affiliation with Plug and Play Tech Center spans years, progressing from Senior Director to Director of Corporate Partnerships. He's a key contributor to nurturing innovation ecosystems, with notable emphasis on Mobility, IoT, Energy, and Smart Cities.
Investor, Plug and Play Ventures
Davis Auksmukst is a seasoned Investor at Plug and Play Ventures based in Sunnyvale, California. With a diverse background spanning both finance and audit roles, Auksmukst has emerged as a vital contributor to the investment landscape.
In his current role, Auksmukst has accrued over five years of experience in cultivating strategic investments in groundbreaking technologies. His tenure at Plug and Play has been marked by a commitment to identifying and supporting innovative startups.
Prior to his venture capital endeavors, he showcased his financial acumen as an internal auditor at Luminor Group, an amalgamation of DNB and Nordea's Baltic operations. His role involved navigating intricate financial landscapes to ensure robust internal controls and adherence to industry standards. A significant part of Davis's journey includes his role as an Internal Auditor at DNB, where he exhibited his prowess in assessing and enhancing the efficiency of financial processes.
Head of Sales, OpenAI
Aliisa Rosenthal currently leads sales and partnerships at OpenAI, supporting enterprise customers building AI integrations into their products. Aliisa started her career in the field of artificial intelligence at Quid, where she held the role of director of strategic partnerships. She then moved on to become the first sales hire at Mixpanel, run enterprise sales at InVisionApp, and served as VP of sales at WalkMe.
Partner, Diaspora Ventures
Marvin Liao is is an Investor-Operator with a remarkable portfolio. As a partner at Rolling Fund Diaspora.vc and manager of the holding company Sukna Global, he wields a profound impact. His prior roles encompassed being a partner and board member at Game Groove Capital, an International Gaming Holding Company. Moreover, he held a significant role as a partner at Venture Capital Fund 500 Startups. There, he not only spearheaded the SF-based accelerator program but also steered investments in Seed stage startups. Throughout his tenure, he championed investments in over 414 pre-seed and seed stage startups.
His distinguished journey also features a decade-plus at Yahoo! as an executive, accumulating extensive operational experience across Asia, Europe, Latin America, and the United States. His reach extends further as he sits on the investment committees and advisory boards of various venture capital funds. Beyond this, he serves as a mentor to numerous accelerator programs globally.
Founding Partner, Blitzscaling Ventures
Chris Yeh has spent his entire career working at high-tech startups. His expertise include online advertising, online marketing, sales management, lead generation, product management, market research, product marketing, entrepreneurship, general management
Blitzscaling Ventures
I have been an active professional in the business and technology sectors in Silicon Valley. As a founder, CMO, industry analyst, and public speaker, I am passionate about discovering the next technology trend, explaining it, and helping it become deployed worldwide.
My career arc has spanned web2, sharing economy, web3, and autonomous/AI technologies. I examine emerging technologies in terms of growth, opportunity, and changing consumer behaviors and expectations.
I began my career as an analyst at Forrester Research and later transitioned to Altimeter Group as a Founding Partner. In 2013, I established Catalyst Companies to concentrate on the emerging collaborative economy and the maker movement. I also co-founded Kaleido Insights. In 2022, I took on the role of CMO at a web3 project called RLY Network Association, funded by a16z, Coinbase Ventures, Battery, and others.
I have appeared in publications such as The Wall Street Journal, The New York Times, USA Today, and Fast Company. I have published research reports, playbooks, and frameworks to help businesses navigate change, enhance customer experiences, and identify trends before they happen.
I frequently speak and present at conferences and events worldwide, including global conferences, corporate kickoffs, TED stages, Web Summit, and host events around the world.
Senior Director, IDEO
I have been an active professional in the business and technology sectors in Silicon Valley. As a founder, CMO, industry analyst, and public speaker, I am passionate about discovering the next technology trend, explaining it, and helping it become deployed worldwide.
My career arc has spanned web2, sharing economy, web3, and autonomous/AI technologies. I examine emerging technologies in terms of growth, opportunity, and changing consumer behaviors and expectations.
I began my career as an analyst at Forrester Research and later transitioned to Altimeter Group as a Founding Partner. In 2013, I established Catalyst Companies to concentrate on the emerging collaborative economy and the maker movement. I also co-founded Kaleido Insights. In 2022, I took on the role of CMO at a web3 project called RLY Network Association, funded by a16z, Coinbase Ventures, Battery, and others.
I have appeared in publications such as The Wall Street Journal, The New York Times, USA Today, and Fast Company. I have published research reports, playbooks, and frameworks to help businesses navigate change, enhance customer experiences, and identify trends before they happen.
I frequently speak and present at conferences and events worldwide, including global conferences, corporate kickoffs, TED stages, Web Summit, and host events around the world.
CEO, Managing Partner, Silicon Foundry
Neal Hansch, CEO and managing partner of Silicon Foundry, draws upon over 25 years of experience in venture capital, product management, technology operations, corporate development, and trusted advisory to steer the firm. Prior to this, he assumed the role of Managing Director for the emerging markets technology training, investment, and incubation program at the Meltwater Entrepreneurial School of Technology (MEST). In this capacity, he led a global team of 150+ professionals, orchestrated over twenty startup investments, and forged partnerships with industry giants like Google, Samsung, and Vodafone.
Neal's professional journey includes a tenure as General Partner at Rustic Canyon Partners (RCP), an early-stage VC fund managing $500 million. He also contributed to the corporate development group at Macromedia (Nasdaq: MACR, acquired by ADBE). In this role, he held responsibilities for global M&A transactions and strategic equity investments, gaining valuable insights into cross-border transactions through extensive travel across Asia.
Principal, Silicon Foundry
John Zamora, Principal at Silicon Foundry, serves as a versatile advisor to members spanning diverse industries, with a specific emphasis on financial innovation. He comes with a wealth of experience, having previously spearheaded strategy and operations at First Circle, a fintech startup in Southeast Asia backed by Series A funding.
His expertise is underpinned by a comprehensive background in investment management, global strategy consulting, and international development. Notably, his contributions have extended to organizations like AllianceBernstein, Albright Stonebridge Group, and USAID. Additionally, John holds FINRA Series 7 & 63 licenses, adding a regulatory dimension to his multifaceted capabilities.
SVP, General Manager, Arise Gaming
John Pompei serves as the Senior Vice President of Customer Success at Arise. His multifaceted role encompasses bolstering business development, orchestrating seamless implementations, and ensuring operational excellence for Arise Gaming clients.
Prior to joining Arise, he held the position of Chief Customer Officer at Officium Labs, overseeing sales, marketing, and service delivery. Preceding this, he was at the helm of global player experience at EA (Electronic Arts), served as DVP of Customer Operations for Sears & Sears Marketplace, and spent a significant 15-year tenure at Microsoft. During his time at Microsoft, he held various leadership positions, notably directing consumer support across Europe, Middle East & Africa, while simultaneously spearheading Global Skype Support.
John Pompei's impact extends beyond roles, as he's recognized as a thought leader in Customer Experience (CX). His strategies and solutions have resonated globally, blending technology and human elements to elevate customer experience. His teams have been acclaimed for their excellence in customer experience and support under his adept guidance.
Chief Digital & Strategy Officer, NTT Data
Maaz Khan thrives at the intersection of technology, business, innovative startups, human-centered experiences, and social good. He possesses a talent for weaving captivating narratives and connecting dots through design thinking, data, and logic, compelling people to take action.
In his capacity, he advises enterprise startups and tech companies on digital strategy, transformation, partnerships, and innovative Go-To-Market approaches. Maaz is a versatile cross-functional leader, collaborating with NTT/Docomo Ventures portfolio firms and the Silicon Valley Ecosystem. His role encompasses strategic business development and fostering opportunities for a symbiotic relationship between NTT customers and partners.
Beyond his professional endeavors, Khan co-founded Global Youth Connection, a microfinance initiative, and played a foundational role in Ideatrr, an innovative ideation platform uniting the world through ideas.
Chief Operating Officer
Singapore FinTech Association (SFA)
Reuben is Chief Operating Officer at Singapore FinTech Association (SFA). He leads the secretariat and works with the executive committee to spearhead initiatives that strengthen the FinTech ecosystem in Singapore. With over 18 years of experience in business development and management, Reuben has empowered both large enterprises, SMEs and government agencies in uncovering valuable revenue and growth opportunities through active business partnering and strong leadership. He has led teams across the industries of aviation, real estate investment, marine, intellectual property, amongst others.
Chief Product Officer
Cake Group
Ng Ying Zhong is the CPO at Cake Group, one of the fastest growing digital assets innovators. Cake Group empowers investors to generate returns on their digital assets through decentralized finance (DeFi) services and applications in a secure and transparent way through its core businesses. Cake Group’s four verticals are Bake, its retail aim; Levain, its institutional arm; Birthday Research, its R&D arm; and Whisk, its VC arm. Zhong steers the key product verticals and research arm at Cake Group. From his initial role as the company's first product manager, he laid the foundation for Cake Group’s product management practice, driving its transformation into a product-led organization. With a dedicated team of over 50 product managers, engineers, and designers, Zhong continues to promote innovation and cultivate growth, facilitating the development of advanced solutions.
In 2022, he was also honored as a Singapore Fintech Leader Under 30, recognizing his significant contributions to the fintech space.
Centre Head
BIS Innovation Hub
Maha is Centre Head, BIS Innovation Hub Singapore. Having been newly appointed, most recently Maha was Head of Department for Early and High Growth Oversight leading the Financial Conduct Authority’s (FCA) response to the Kalifa review of Fintech. A Senior Leadership Team member, she is setting up this new department from the ground up as part of the FCA’s strategy. Prior to this, Maha served as Chief Payments Officer at Pay.UK on secondment from the FCA, responsible for running the payments operations of BACS, Faster Payments, Image Clearing Services and related managed services.
Maha joined the FCA in 2017 to set up the first Payments Department and was responsible for crafting and implementing the FCA supervisory strategy for the UK Payments Sector. This included leading the implementation of the Second Payments Services Directive (PSD2) and Open Banking.
Projects Manager & Advisor
BIS Innovation Hub – Singapore Centre
Benjamin Lee is the Projects Manager & Advisor for the Bank for International Settlements Innovation Hub (BISIH) in Singapore. He was seconded to the BISIH through the Monetary Authority of Singapore (MAS) and worked to establish and launch the centre, and to manage its projects pipeline. The BIS Innovation Hub is a joint initiative by the BIS and its partner central banks to identify and develop in-depth insights into critical trends in technology affecting central banking; develop public goods in the technology space geared towards improving the functioning of the global financial system; and serve as a focal point for a network of central bank experts on innovation.
Prior to this appointment, Lee spent most of his career in central banking at the MAS, where he worked on international finance matters, and at the Ministry of Finance in Singapore, where he worked on public finance administration matters. Lee has also served as Singapore's representative to the Executive Board of the World Bank Group and was based in Washington DC between 2014 - 2016.
Advisor
BIS Innovation Hub
Kah Kit is an Advisor at the Bank for International Settlements Innovation Hub (BISIH) in Singapore. He leads policy and governance work in next-generation financial market infrastructure projects such as Project Nexus which aims to interlink fast payment systems to enable instant cross-border payments. He also provides policy support for Project Mandala which seeks to develop compliance-by-design architecture to enhance cross-border payments. Aside from project contributions, he also represents the BISIH on the Governance and Oversight workstream of the Committee on Payments and Market Infrastructures (CPMI), providing insights and practical learnings to contribute to the G20 cross-border payments programme.
Kah Kit is a secondee from the Bank Negara Malaysia (BNM) with over 16 years’ experience ranging from legal advisory and prosecution of financial crimes to policy development in the areas of payments, fintech and digitalisation. At BNM, he was instrumental in spearheading Malaysia’s migration to digital payments and foster the development of interoperable real-time payments. He also led the Digital Currency Research Hub where he was responsible for developing policies and strategies on CBDC and digital assets.
Advisor
BIS Innovation Hub
Sonja is an Advisor at the Bank for International Settlements Innovation Hub (BISIH) Singapore leading the Hub’s central bank digital currency (CBDC) program. In this position, she leads project Mandala and co-leads project Mariana. Davidovic is seconded from the Monetary Authority of Singapore while on leave from the International Monetary Fund (IMF).
At the IMF, Davidovic worked as Economist and Digital Expert on Transformative Technologies. In that position, she provided capacity building, policy recommendations and technical advice to IMF member countries on digital currencies, including CBDCs. In addition to numerous analytical and research papers on financial technology and digital currencies, she also contributed to the analytical work for the G20 agenda to enhance cross-border payments. Immediately prior to joining the BIS, Davidovic worked as Market Infrastructure Expert on the digital euro investigation phase at the European Central Bank (ECB).
Ecosystem Development Manager
NUS Enterprise
A holistic marketer with more than 10 years’ experience in marketing and communication for, in particular, tech industry. Has a broad and integrated perspective in developing, designing and implementing marketing programs and activities.
Business Development Manager & CEO Liaison Officer
SSenStone
Taeyoung Kim (TK) is a professional with experience in finance and cyber security, currently serving as the Business Development Manager and CEO Liaison Officer at swIDch Ltd. Her previous roles at Lloyds Banking Group, Fujitsu Korea, and STX Offshore & Shipbuilding demonstrate her expertise in financial analysis, client relationship management, and compliance.
Chief Growth Officer
Bytesforce
Arun Sangwan currently holds the position of Chief Growth Officer at Bytesforce Corporation, a leading Insurtech based in Singapore. With a focus on sales, marketing, and partner ecosystems, he is dedicated to scaling up the business and expanding Bytesforce into new markets while strengthening partner relationships. Sangwan brings extensive experience from roles at Neutrinos and Citrix, where he demonstrated a talent for driving innovation and fostering strategic growth.
Regional Director
BLOCK71 Southeast Asia
Hui Hong Seow is a seasoned professional known for her achievements in entrepreneurship, policy development, and innovation. Currently, she serves as the Regional Director at BLOCK71 Southeast Asia, where her role involves ecosystem building and strategic operations. With a background that includes roles such as Venture Fellow at Insignia Ventures Academy and Head of Revenue at Ablr, Hui Hong has left her mark on organizations like MiRXES, BlueChilli Group, raiSE SG, SG Enable, and the Ministry of Trade and Industry (Singapore).
Director of Senior AI Solution, 4 Paradigm
Christine is the designer of the "4 Paradigm Delivery Standardisation of Project Management Performance", and the architect of the early-stage KEY for delivering AI projects in the 4 Paradigm, effectively putting "AI empowers business" into action. Christine has extensive experience in decision-making AI solutions and large-scale online service architectures, such as the Intelligent Real-time Banking Risk Control System and the Personalised Marketing System. She is also well-versed in developing applications for big data and machine learning systems.
Head of Data Science Team, 4 Paradigm
Mr. Li Bin was a Data Scientist at China PingAn Group Financial OneAccount from 2018-2020. He was responsible for the design and implementation of AI solutions for the financial industry. He served as the AI product manager in the company and successfully designed and launched AI capability products such as voiceprint signature and application material forgery recognition.
From 2020 to the present, he has been the head of the data science team at 4 Paradigm. He is responsible for the implementation of the "Polaris" experimental science business on the enterprise side. He has provided AI consulting and implementation services for several state-owned banks and joint-stock banks, covering key areas such as risk control, retail marketing, and customer service efficiency.
Chief Architect, Du Xiaoman Financial
Li Feng brings a wealth of experience in IT and the Internet to his role. He specialises in designing and researching financial distributed systems, middleware, and foundational platforms. His responsibilities extend to strategic planning and technology development at Du Xiaoman, where he has led the evolution of credit technology from 1.0 to 4.0, significantly boosting business growth.
In the field of fintech, Li Feng has spearheaded ground-breaking research and successful implementations in areas like blockchain, complex engineering technology, virtual reality, and IoT. Notably, he established Baidu's first-ever blockchain R&D team. His work has gained global recognition, including Forbes Global Blockchain 50, Harvard Business Review accolades, and recognition from the Ministry of Industry and Information Technology.
Li Feng is a distinguished industry expert who has actively contributed to national standards, authored various white papers and blue papers, and personally filed over 60 international and domestic invention patents.
Director of Financial Industry Solutions, JD Technology
Jiaoyao worked for multiple world-renowned companies such as Canon, ABeam Consulting, Yiqianbao (a mobile payment platform under PingAn Group), and China Construction Bank prior to joining JDT (JD Technology). With extensive cross-industry work experience in financial technology, the internet, consulting, and IT, he has a unique perspective on a wide range of subjects, including big data models, blockchain, inclusive finance, digital transformation, intelligent data platforms, digital marketing, and operations.
Executive Director and Vice President, MYbank
Mr. Jiang Hao has more than 20 years of experience in the financial industry. He previously served as the Senior Deputy Manager of China Construction Bank, Vice President of the Shanghai Branch of Bank of China (Hong Kong) Limited, Head of Retail Credit at Bank of Shanghai Head Office, Chief Compliance Officer of BOSC Asset, and Personal Banking Director of Bank of East Asia (China) Limited, among other executive roles. He joined MYbank as the Chief Compliance Officer in May 2018. He has served as the Secretary of the Board of Directors and the Chief Compliance Officer of MYbank since July 2020 and has served as the Vice President of MYbank since September 2021.
Co-CEO, LianLian International
Shen Enguang joined the company in September 2020 and held the positions of Vice President, Director of the Foreign Exchange Business Department, and Director of the International Financial Cooperation Department. He is currently co-CEO at LianLian International, overseeing foreign exchange business, B2B business management, international banking cooperation, and communication.
Head of Banking Cooperation Department, LianLian International
Ma Xiao joined LianLian in June 2021 and is responsible for domestic and international financial institution affairs. Prior to this, he worked at a well-known foreign bank, specialising in international payment settlement business. With over ten years of experience with financial services such as cash management for large foreign-invested enterprises in China, he has extensive knowledge and experience in international payment settlement products, services, compliance regulations, etc.
Chairman, TrustDecision; Co-founder and Partner, Tongdun Technology
Jackal has 30 years of working experience covering North America, Australia, Asia, and Europe. He is a seasoned technology and business executive, with previous experience including: Senior Engineer at IBM China/Hong Kong/Canada; Head of Technology Planning at Royal Bank of Canada; Chief Architect of Hong Kong Octopus Card System; Asia Regional Head of Operation at AXA insurance; President at EDIFY Asia, a JV between the US and China; Managing Director at Aspect Software for North Asia. He is an advisor and consultant at various business/technology transformation initiatives such as Citibank, HSBC, Standard Chartered, PingAn Insurance, China Construction Bank, and Pudong Development Bank.
China including the Ministry of Industry and Information Technology, National Development and Reform Committee. He was also VP of Asia Pacific at Threat Metrix, and co-founded Tongdun Technology.
Strategic Planning Expert, Strategic Planning Management Headquarters, Hundsun Technologies
At Hundsun Technologies, Zhichen is in charge of strategy planning and market insights. He possesses deep understanding of the digital transformation occurring in the insurance and banking industries, along with creative applications of financial technology. Previously, he led projects such as the non-trade finance blockchain platform of the Industrial and Commercial Bank China and the cross-border financial services platform of the State Administration of Foreign Exchange.
GM, Retail R&D Centre of Financial Technology Division; Co-President, Basic Retail Business Unit, PingAn Bank
Mr. Chu Liang served in various management positions at PingAn Group headquarters, PingAn Technology, and PingAn Bank. As Assistant General Manager and Chief Architect of PingAn Technology, he was responsible for product incubation and implementation in areas such as multimedia contact center, Internet, and mobile technology. He led major technology projects like PingAn Bank mobile banking, Orange Banking, and channel integration between the two banks.
He transferred to PingAn Bank in August 2016 and participated in the transformation of PingAn Bank's retail business as the chief technology leader. He set up the retail technology development team, fully implemented the agile development model and organisational governance, and led the team in technological exploration, research, and application innovations. He promoted the retail AI Banker project, systematically applying technologies like face recognition, OCR, big data, and AI to marketing, service, and risk business areas.
GM, Basic Middle Platform R&D Centre, Financial Technology Division, PingAn Bank
With over 20 years in banking IT, Mr. Liu has worked on large-scale projects and conceptual architectures like data services, big data governance, and AI banking applications. He has been deeply involved in the field of banking data governance and big data applications, contributing to CBRC's "big data governance of commercial banks" white paper.
In 2019, Mr. Liu joined PingAn Bank, leading the digital transformation of intelligent risk control and building a new digital risk control platform. His work earned awards from Gartner, The Asian Banker, and the People's Bank of China, and contributed to the Group's "Finance + Technology", "Finance + Ecology" and other strategic transformations.
Innovation Experiment Team Leader, Financial Technology Division, PingAn Bank
Zeng Yang is engaged in product innovation in AI, WEB3, domestic and international payments, etc. He joined PingAn in 2023 and is now deeply involved in PingAn Bank's fintech innovation business. He is committed to empowering the bank's digital transformation through technological and business innovation. Prior to joining PingAn, he worked for renowned enterprises such as China Minsheng Bank and ByteDance. He also co-founded and served as CTO of a UnionPay full-category filed aggregated payment service provider company. With 11 years of rich experience in financial technology product innovation and domestic and international market practice, he brings a wealth of knowledge to his role.
Chief Investment Officer, Micro Connect
Dr. Lin is Chief Investment Officer of Micro Connect. He and his team lead the firm’s efforts in investment portfolio construction, risk management, asset securitisation and fundraising.
Dr. Lin has decades of investment experience in both private and public markets. Prior to Micro Connect, Dr. Lin was one of the Founders and CEO of Goldstream Investment, a listed multi-asset and multi-strategy hedge fund platform. He managed quantitative investment portfolios and is a recipient of ‘Golden Bull’ Fund Manager Award. He was also a Partner and Managing Director of Hony Capital, a private equity firm in China. Dr. Lin also worked at China International Capital Corporation (CICC HK), Asian Development Bank (Manila) and the World Bank (Washington).
Executive Vice President, WeBank
Qiao became one of the primary members of WeBank's founding management team since April 2014 and has overseen the bank's strategic development and the incubation of innovative businesses, including wealth management, auto finance, SME loans, virtual credit cards, and international collaborations. He took on the position of Head of Financial Markets and Interbanking in 2020 and has been responsible for WeBank's financial asset management, FICC (Fixed Income, Currencies, and Commodities), asset securitisation, and interbank business ever since.
He's also been a Global Partner at McKinsey & Company in Chicago, Hong Kong, Taipei between 2005 and 2014, overseeing retail financial services in Asia, and serving as the regional leader for digital financial services, innovative businesses, and financial institution operations in Asia.
Senior Consulting Manager, Financial Technology Division, iFLYTEK
Pan Tao is currently in charge of AI financial solutions in the South China region. He has rich practical experience and profound insights into the application of artificial intelligence in the finance industry. He has led projects such as the intelligent services for the national hotline of China Merchants Bank and the intelligent precision marketing of Bank of China's Shenzhen branch.
Co-CTO, Linklogis
With over ten years of experience, Xu Yan is recognised as a remarkable pioneer in AI research and industrialization. He has received the Youth Science Fund, Postdoctoral Fund, and the Best Student Paper from the China Computer Federation's Artificial Intelligence Committee. One of his papers has been cited 700 times in total. Among his major achievements are the development of a personalised new recommendation system, a complicated network-based anti-fraud system, an AI Doc Check system, and a variety of other smart automation solutions.
Founding Partner, Jadestone Capital
Jay Huang is a founding partner at Jadestone Capital. Previously he was a managing director at Intel China. Prior to joining Intel, Jay was Vice President of Nortel Greater China and then Vice President of Nortel Asia.
Vice President, Enterprise Service, Alibaba Cloud
William XIONG is the Vice President of Alibaba Cloud, responsible for the Enterprise Service Cloud portfolio, which includes Energy Cloud, Sales & Procurement Cloud, Financial Cloud, Marketing Cloud, and the Enterprise Mobile Application Development platform. With a broad knowledge base in software and mobile development, e-wallets, insurance, data platforms, and carbon neutrality, William brings extensive expertise to the role.
Prior to Alibaba Cloud, William was the Senior Director of Technology at Ant Group, where he oversaw the development of international payment technology. Concurrently, he held a significant position as CTO of Worldfirst, leading the roll-out and partnership of e-wallets in numerous countries such as Paytm in India, Dana in Indonesia, TNG Digital in Malaysia, Kakaopay in Korea, Ascend Money in Thailand, Mynt in the Philippines, Easypesia in Pakistan, bKash in Bangladesh, among others. He and his team are committed to bringing inclusive, end to end, value driven cloud-based services and products to enterprises.
CTO, ZOLOZ (a wholly-owned subsidiary of Ant Group)
As CTO of ZOLOZ, a security technology-focused subsidiary of Ant Group, William Yao also holds a prominent role on the China Computer Federation Expert Committee on Big Data (CCF ECBD). Before this, he was the CTO of Ant Bank in Hong Kong and led the technical team for Alibaba Cloud’s CDN. A staunch advocate for open-source software, William Yao boasts over 15 years of expertise in the internet and fintech sectors.
Executive Chairman, Human AI Pte Ltd
Bank Board, Strategy, Risk and BRNC, Rakbank
Board member, Pulse Global and SBCo
Steve Monaghan is Executive Chairman of Human AI Pte Ltd, serves on the Bank Board, Strategy, Risk, and BRNC committees of Rakbank, is a board member at Pulse Global and SBCo, a Limited Partner and investment committee member in True Global Ventures, and a private investor in AI, Quantum Computing and Fintech. Originally a commercial pilot, Monaghan held senior corporate and banking roles in product, marketing, operations, innovation and general management. He worked for leading corporations and financial institutions including Dell, Compaq, Citigroup, OCBC, Shinsei, DBS Bank and AIA. As founding Chief Innovation Officer for DBS Bank, he drove the innovation agenda focused on Payments (PayLah), SME (Business Class), GTS (Working Capital Advisory), AI, and Big Data, culminating in the $220+M investment of DBS in innovation projects, including DBS A*Star R&D Lab, DX transformation (dbs.com), Digital Onboarding, and DBS Digital Banking. Throughout his career, Monaghan has specialized in introducing new business models, businesses, and products in all major Asian markets and has filed 6 patents in FinTech.
Chief, Digital Strategy & Leadership
National University of Singapore (NUS-ISS)
Damien Cummings is one of Asia Pacific's most recognised digital transformation leaders. Damien is currently the Chief, Digital Strategy & Leadership practice at the National University of Singapore (NUS-ISS). Prior to that he was the founder & CEO of HR tech/SaaS company, Peoplewave. Before entrepreneurship, he was Global Head of Digital Marketing at Standard Chartered Bank and Chief Marketing Officer at Philips APAC. Cummings has also worked at major global brands such as Samsung, Dell, Ogilvy, Coca-Cola and McKinsey & Company.
Lead Partner of Technology Strategy, KBC Global Partners
Board member, DEC Institute
Prof Keith B. Carter guides businesses and governments on leadership development in emerging technology. Lead partner of technology strategy at KBC Global Partners and the founder of JustAskProf.com, Carter stands at the forefront of innovation, challenging businesses and governments alike to think differently and to utilize technology in ways that can revolutionize our world. He sees there is a tremendous gap between what it takes to win vs. the skills and capabilities board members, senior leaders and midcareer professionals had learned in school 20 years ago. He helps with policy setting and global thinking to solve these problems as board member at DEC Institute in Switzerland and Bretton Woods Committee member in Washington DC.
Innovation Incubator, Futurist, Author of ‘Econovation’,
Founder and Managing Director, IdeaFaktory Innovation
Steve Faktor is an innovator, futurist and digital commerce expert. His company IdeaFaktory, helps companies accelerate growth by partnering with top startups, developing new innovations, and restructuring for growth. In his role as the Managing Director of IdeaFaktory Innovation, Faktor offers insights to financial services, tech, and consumer goods companies. He guides them through future scenario planning, empowering them to thrive in the evolving landscape. IdeaFaktory, nurtures dynamic young start-ups and aids in transforming older ones with innovative ideas. Previously, as a senior executive at American Express, Citi and MasterCard, Faktor has created several $150M+ businesses and deployed multiple enterprise innovation programs. His book Econovation, talks about capitalizing on the end of consumerism and rise of 'producerism'. Faktor is a LinkedIn Top Voice with over 730K+ followers, a testament to his industry impact. Faktor has garnered recognition in distinguished media outlets such as Forbes, Harvard Business Review, NPR, The Wall Street Journal, Bloomberg Radio, and MSNBC.
Professor, Design Group, Stanford University
Barry Katz has authored eight books, including "Change By Design" with Tim Brown (Harper Collins, 2009/2019), which explores design thinking as a business strategy; "NONOBJECT" with Branko Lukic (MIT, 2010), a conceptual exploration of "the space between person and product;" "Make it New: The History of Silicon Valley Design," translated into Japanese, Chinese, Korean, and Spanish; and "Healthcare by Design" (University of Toronto Press). He is currently working on his new book, "The Architecture of Information: Structure and Symbol for the Age of Data." His writings on design as a strategy for innovation have been featured in numerous academic, professional, and popular journals. Additionally, Katz serves as a Professor of Industrial and Interaction Design at the California College of the Arts, served as Adjunct Professor in the Design Group, Department of Mechanical Engineering, at Stanford University. As IDEO Fellow Barry worked for more than 20 years with the world’s leading design and innovation consultancy, and continues to consult with governments, companies, and academic institutions worldwide.
Advisor, Bank for International Settlements (BIS) Innovation Hub
Hakan Eroglu is an Advisor for Technology & Innovation at the Bank for International Settlements (BIS) Innovation Hub in Hong Kong with a focus on Open Finance, Digital Currencies and Payments. Before joining the BIS, he was the Global Open Banking & Open Data Practice Lead at Mastercard, based in Zurich. He is an expert for open data ecosystems, open banking & open finance regulation, API standardization, instant and cross-border payments. Eroglu is an internationally recognized thought leader in his area of expertise, and member of various international working groups. He brings more than 14+ years of technology & strategy consulting and product development experience at Mastercard, Accenture and Infosys – in Europe, the Middle East, Latin America and Asia Pacific.

CEO
Alex.Bank
CEO of Alex.Bank Simon Beitz has over 20+ years’ of experience in the retail and business banking sector across start-ups, banking, finance, and technology. With a background at institutions like Suncorp Bank, he pioneered the Innovation Lab, fast-tracking the implementation of new customer propositions. As a co-founder of EML Payments, now an ASX-listed payment solutions business, Beitz brings a wealth of experience. Alex Bank focuses on delivering a humanized banking experience. This involves eliminating complex paperwork, jargon, and unnecessary fees, reflecting their commitment to restoring a 'human-touch' to banking. In 2024, Alex Bank is the most awarded new digital bank in Australia having received its full ADI in December 2022.
Founder and CEO
Qraft Technologies
With a professional history spanning over 24 years, Hyungsik Marcus Kim is the Founder and CEO of Qraft Technologies, based in Seoul, South Korea. His extensive experience and keen insights into quantitative and algorithmic trading models laid the foundation for the establishment of Qraft Technologies in 2016. Kim brings to the table a robust background in the AI-driven ETFs Management System and AI Execution System, showcasing his deep expertise in these key areas. Under his leadership, Qraft has emerged as a prominent entity in the field of artificial intelligence-driven investment solutions. Qraft’s exclusive AI investment engines and signals cater to over 20 financial institutions globally, providing a range of solutions from signal subscription to customized portfolio construction. With a current Assets under AI (AUA) valuation of 1.8 billion USD, Qraft's proprietary Machine Learning and Deep Learning techniques set them apart in various areas, including (i) Security selection & portfolio construction, (ii) Asset allocation & model portfolios, (iii) AI-powered electronic trading, and (iv) AI Risk indicators.
FManaging Director (Head of Client Coverage), Qraft Technologies
Vincent Kim is the Managing Director and Head of Client Coverage for Qraft Technologies since 2024 with around 20 years of experience in the financial services industry.
Prior to his current role, Vincent was Head of International Banking in the J.P. Morgan Seoul branch, responsible for the overall banking relationship with multinational clients of the commercial bank. Before joining J.P. Morgan in late 2014, Vincent was at Royal Bank of Scotland plc in Korea, where he worked in corporate trade sales and as a coverage banker for Korean corporates from 2011. Prior to that, Vincent was at ING Bank N.V., within the Asia Desk of Wholesale Banking as relationship manager covering subsidiary clients in the European region from 2007 to 2011.
Founder & CEO
Qraft Technologies
With a professional history spanning over 24 years, Hyungsik Marcus Kim is the Founder and CEO of Qraft Technologies, based in Seoul, South Korea. His extensive experience and keen insights into quantitative and algorithmic trading models laid the foundation for the establishment of Qraft Technologies in 2016. Kim brings to the table a robust background in the AI-driven ETFs Management System and AI Execution System, showcasing his deep expertise in these key areas. Under his leadership, Qraft has emerged asIZEN a prominent entity in the field of artificial intelligence-driven investment solutions. Qraft’s exclusive AI investment engines and signals cater to over 20 financial institutions globally, providing a range of solutions from signal subscription to customized portfolio construction. With a current Assets under AI (AUA) valuation of 1.8 billion USD, Qraft's proprietary Machine Learning and Deep Learning techniques set them apart in various areas, including (i) Security selection & portfolio construction, (ii) Asset allocation & model portfolios, (iii) AI-powered electronic trading, and (iv) AI Risk indicators.
CEO, AIZEN
Jung Seok KANG is the CEO of AIZEN. AIZEN’s mission is to serve as a trusted partner to our clients by providing an AI financial technology platform that enables them to expand and grow their business.
Under Mr.Kang’s leadership, AIZEN has received multiple accolades, including the Finance Minister Award in Korea, recognition from the Ministry of Science and ICT, the Prime Minister Awards, and the company was honored with the MAS Fintech Award in 2020.
Previously, Mr. Kang assumed various roles at Citigroup, and served as a chief of staff to the Former Minister of Finance at the National Assembly of Korea. In addition to his public and private sector roles, he made an early investment in Wipower, a company specializing in wireless charging technology, which was successfully acquired by Qualcomm.
Mr. Kang holds a B.S. in Linguistics and an M.S. in Economics from Seoul National University, along with an MBA from the University of Chicago Booth School of Business.
Strategic futurist; Expert advisor on AI, blockchain, and the Metaverse; Author; Founder of Datafloq
Mark van Rijmenam is a renowned strategic futurist and the author of ‘Step into the Metaverse: How the Immersive Internet Will Unlock a Trillion-Dollar Social Economy’. As the founder of Datafloq, a well-known global platform for emerging technologies, he offers unique perspectives on the convergence of generative AI, blockchain, and metaverse. His expertise is in understanding how these technologies can transform industries, such as the immersive internet, while also highlighting the associated risks. Rijmenam is a trusted advisor to top organisations and governments, as well as a leading voice in navigating the complexities of digital innovation.

CEO, Buysell Standards
Bumjun Shin, the CEO of BuySell Standards, has propelled the company into a pioneering position in the financial technology realm. Founded in March 2019, the company, under Shin's guidance, swiftly gained recognition and success. The 2021 launch of the 'PIECE' fractional investment platform, selling out its first portfolio within 30 minutes, marked a significant achievement. Designated a 'Venture Company' by the Ministry of SMEs and Startups, BuySell Standards entered into a pivotal blockchain consulting agreement with Kearney. Elected as the first chairman of the Token Securities Council of KORFIN in 2022, Shin's commitment to innovation and sustainable development has solidified BuySell Standards as a frontrunner in fintech.

President, Korea Fintech Industry Association (KORFIN)
Keun Ju Lee has built a distinguished career within the fintech industry, marked by his extensive tenure at the Industrial Bank of Korea (IBK) from 1983 to 2015. Throughout his time at IBK, he held various pivotal roles, including overseeing the New York Branch, leading smart finance initiatives, and managing IT, digital finance, and fintech operations. In 2016, Lee played a crucial role in establishing KORFIN, where he served as its Establishment Preparatory Director. Presently, he holds esteemed positions as the president of the Korea Fintech Industry Association and the CEO of Hanpass. Additionally, Lee imparts his industry insights as an adjunct professor at Dongguk University's Graduate School of Business.
Director, Web3 Business Team, SK Telecom
Jongseung Kim boasts over two decades of expertise as an ICT professional within the telecommunications sector. Since 2017, he has spearheaded blockchain initiatives at SKT. Under his leadership, notable milestones include the commercialization of Korea's inaugural DID (Decentralized Identifier) reliant mobile identity and authentication service, 'initial', in 2019. Furthermore, in 2022, Kim oversaw the successful launch of 'TopPort', a pioneering fiat payment driven NFT marketplace. Most recently, he orchestrated the introduction of 'T wallet', a cutting-edge web3 wallet service with multi-chain support.
Global AI & Digital Innovation Expert
Lecturer, University of Hong Kong
Holds a PhD in artificial intelligence and has spent his career building AI inside global banking — including as Chief Digital Officer of HSBC Germany and head of AI research at HSBC's innovation lab in Hong Kong. He lectures on generative AI in finance at the University of Hong Kong.
Board Member, Africa Fintech Network
Global AI Policy Leader
A leading voice in Africa's fintech and AI ecosystem, he is president of the Fintech Association of Botswana and co-founder of Xavier Africa, an AI and digital transformation company. He is recognised for bridging technology and policy — shaping AI governance frameworks that enable innovation while protecting consumers.
Former Global Head, Enterprise
Architecture & Technology Strategy, Standard Chartered
Led a US$1bn+ global technology and enterprise architecture agenda across more than 30 markets at Standard Chartered, shaping the bank's digital, data and AI strategy. He is now CEO of Xponential, Chief Digital Officer at Siam Piwat Group, and advises boards on practical AI adoption through Pivot Digital.
Technology Leader; former Global Head of Enterprise Architecture & Technology Strategy, Standard Chartered
Axel Winter is a highly experienced technology leader with strong hands-on experiences in the banking, retail and start-up worlds. He was previously Global Head of Enterprise Architecture & Technology Strategy for Standard Chartered Bank and had similar roles at GE Money and Cisco Systems. He has consulting experience at Accenture and Deloitte, and has recently founded a corporate start-up partnering with Grab and JD.Com. He is currently the Chief Digital Officer for a luxury mall operator and advises start-ups in asset tokenization and eCommerce. His expertise in technology infrastructure for banks and large businesses makes him a valuable contributor.
Chief Investment Officer, Buysell Standards
Bob Jang has a rich background in the financial sector. From March 2010 to March 2015, he served on the Clearing & Settlement Commission at the Korea Exchange, demonstrating his expertise in financial regulations and operations. Notably, he has held pivotal roles across prestigious organizations: Managing Director at Hanwha Asset Management, where he directed cross-border investment strategies; at Hyundai Asset Management, he led strategic solution initiatives; and as Executive Director at Goldman Sachs Asset Management, he was instrumental in global operations and portfolio management.
CTO, Toss Bank
Junha Park, currently the Chief Technology Officer at Toss Bank, has significantly impacted the fintech landscape since joining in 2020. Previously, he was a tech lead at Viva Republica, driving innovation and technology solutions. His career includes a pivotal role as Vice President of mobile application service development at various startups, enhancing user experience and service delivery. Before his startup journey, he honed his development skills at Naver from 2004 to 2012, contributing to its growth and technological advancements.
Director, Invest Seoul
Bonhi Gu is the director of Invest Seoul, an investment promotion agency of Seoul Metropolitan Government. He is truly enthusiastic about making Seoul a leading hub of global business, innovation, and talent in Asia. Most recently Mr.Gu has been leading work for WOORI BANK KOREA. There, he served as an investment banking manager & derivative trader in London & Seoul. From 2011-2015, he led the Global Business Department where he handled both HR issues and budget management of overseas networks and employees. Also, he contributed to the company by launching banking products for global Wealth Management clients. His work has taken him to WOORI BANK EUROPE GmbH in 2016 as a founder & CEO, where he mainly focused on corporate banking business, money intermediary, and bond trading business.
Manager, Seoul Fintech Lab
At Seoul Fintech Lab, she has supported startups expanding globally for three years, establishing partnerships with international institutions and aiding collaboration with banks for open innovation initiatives.
Venture Capital Specialist
Sung Eun Kim specializes in CVC investments and FI investments in financial companies (life, fire insurance). She has deep insights in the evaluation of promising companies in fintech, AI-powered SaaS, lifestyle, and healthcare platforms.
WEB3 Team, LG CNS
Heejin Dan, a prominent member of the LG CNS_WEB3 Team, brings a wealth of experience in digital banking and innovative infrastructure development. Her notable contributions include leading efforts in the Bank of Korea's CBDC feasibility test, driving the development of the Mirae Asset Security Token platform, spearheading the Bithumb Meta NFT platform project, and playing a crucial role in the near-complete Korean IT Financial Platform project, which is based on Blockchain technology, further cementing her role as a leader in the intersection of finance and technology.
CTO, Toss Bank
Junha Park, currently the Chief Technology Officer at Toss Bank, has significantly impacted the fintech landscape since joining in 2020. Previously, he was a tech lead at Viva Republica, driving innovation and technology solutions. His career includes a pivotal role as Vice President of mobile application service development at various startups, enhancing user experience and service delivery. Before his startup journey, he honed his development skills at Naver from 2004 to 2012, contributing to its growth and technological advancements.
Leader, Seoul AI Hub
Professor, Center for Industrial Collaboration, Seoul National University AI Research Institute
Chanjin Park currently spearheads the Seoul AI Hub, focusing on nurturing AI startups with support from the Seoul Metropolitan Government and execution by Seoul National University's AI Institute. As a Professor involved in Industry-University Cooperation at this institute, Park drives the fusion of academic research and industrial practice, enhancing AI technology's progression. Notably, Park contributed significantly as the software architect for LG's pioneering webOS TV, setting new standards in smart TV innovation. At SK Hynix, Park led AI initiatives addressing complex data challenges in the semiconductor industry, boosting yield and efficiency, showcasing AI's practical value in high-tech sectors.
Head Faculty, The Banking AcademyFounder, TAB Global
Emmanuel Daniel is an author, entrepreneur and corporate strategist whose work explores the future of finance and its impact on business, geopolitics and society. He was named among Clarity Group Global’s Global 50 Thought Leaders in Banking in 2026 and a top 10 global influencer in the “Fintech Power50” list in 2021 and 2022.
His first book, The Great Transition – the personalization of finance is here, published in September 2022, examines how banking is evolving from platform-based services towards personalised finance. It features forewords by former US congressman Barney Frank and financial innovator Richard Sandor. His second book, Building the AI Bank – Speed, Judgment and Power, explores how artificial intelligence is reshaping bank governance, operating models and decision-making.
Emmanuel founded TAB Global in 1996. Through its platforms, including The Asian Banker, Wealth and Society, The Banking Academy, TAB Insights and The Banking conversation he engages with banking and financial services leaders worldwide. He won the Citibank Excellence in Business Journalism for Asia in 1999 for his work on the internet in banking. A speaker and adviser to public and private sector institutions, Emmanuel contributes perspectives on financial innovation, leadership and institutional change.
Founder, TAB Global
Emmanuel Daniel is the founder of TAB Global which includes The Asian Banker, Wealth & Society, RadioFinance, The Banking Academy and The Skill Store. He is an award-winning writer and author with a background in management consulting. He previously served in several government advisory councils, interviewed some of the leading chairmen, chief executive officers, policy makers and entrepreneurs around the world and currently consults with banks on investor, media relations and strategy formulation. His first book on the future of the finance industry, “On the Eve of Finance 5.0”,is set to be published soon.
Founder, TAB Global
Emmanuel Daniel is the founder of TAB Global, which includes The Asian Banker, Wealth and Society, RadioFinance, The Banking Academy and The Skill Store. He is an award-winning writer and author with a background in management consulting. He previously served in several government advisory councils, interviewed some of the leading chairmen, chief executive officers, policymakers and entrepreneurs around the world, and currently consults with banks on investor and media relations and strategy formulation.
President and Managing Editor, The Asian Banker
Foo Boon Ping manages The Asian Banker’s publishing and research business in Asia Pacific, the Middle East and Africa. He regularly engages the financial services community on transformational issues shaping the industry; speaking at and chairing many of the Asian Banker’s as well as partners’ events. He has more than 25 years' experience in strategic brand management, corporate & marketing communication and research & consulting, covering: retail, corporate and transaction banking, financial markets, risk management, compliance and financial technology. He had previously served in senior management positions at UOB and DBS Bank. He was also formerly a senior consulting manager at Ernst and Young and started his career as a financial journalist.
Chief AI Officer, AI Innovation Center, Linklogis
With over ten years of experience, Xu Yan is recognised as a remarkable pioneer in AI research and industrialization. He has received the Youth Science Fund, Postdoctoral Fund, and the Best Student Paper from the China Computer Federation's Artificial Intelligence Committee. One of his papers has been cited 700 times in total. Among his major achievements are the development of a personalised new recommendation system, a complicated network-based anti-fraud system, an AI Doc Check system, and a variety of other smart automation solutions.
Chief Technology Officer, Lexin Fintech
Mr. Erwin Yong Lu joined Lexin in February 2021 and has served as our chief technology officer since then Mr. Lu has over 20 years of experience in the technology sector and has held various senior positions. Prior to joining us, Mr. Lu served as the chief information officer of Ping An Life Insurance. Prior to that, he served as the chief technology officer and vice president for SINA mobile, a leading online media company in China. From 2016 to 2017, he was the chief technology officer of 51Talk (NYSE:COE), a leading online education platform in China. He also worked from 2014 to 2016 as the general manager of the advertisement division at Weibo Corporation, a NASDAQ listed leading Chinese social media company. From 2012 to 2014, Mr. Lu worked at Facebook in Seattle as a software engineer. Before that, Mr. Lu worked at Microsoft in Seattle from 2003 to 2012 as a senior software engineer. Mr. Lu received his master's degree in computer science from the University of Denver in 2003 and a master's degree in chemistry from Zhejiang University in 1998. Mr. Lu is also a named contributor in five IT patents in the United States.
Chief Executive Officer, OneConnect Financial Technology (International)
Matthew Chen is the CEO for OneConnect Financial Technology Co. Ltd (International) (NYSE: OCFT / HKEX: 6638), a leading technology service provider for financial institutions. OneConnect is the Fintech arm of Ping An Group which ranks 33rd on 2023 Fortune Global 500 and 16th on 2022 Forbes Global 2000. In his current role, Matthew is responsible for leading OneConnect SEA leadership team to oversee the day-to-day operations of OneConnect International, provides strategic directions to drive the organisation’s growth in the international market.
Matthew has more than 30 years of experience and knowledge in Banking and Finance, specializing in Treasury, Risk Management and Core Banking domain. Under his exceptional strategic leadership, he has led countless Treasury, Risk Management and Core Banking projects all over Australia, Japan, South Korea, Singapore, Malaysia, Philippines, Thailand, Indonesia, Vietnam, Hong Kong, Macau, and the UAE.
Matthew also acts as the Regional Director for Professional Risk Managers’ International Association (PRMIA), an American based non-profit professional risk managers’ association.
Senior Vice President at Micro Connect
Yanshan Hao, also known as Jim Kok, is currently the Senior Vice President at Micro Connect. He has previously served as the General Manager of the Financial Market Department at JDT, managing a structured credit fund of 2 billion, and has also worked in the structured derivatives business at J.P. Morgan. Jim is a Chartered Financial Analyst (CFA), with an MBA from Yale University, a Master's degree in Mathematical Finance from the University of Southern California, and a Bachelor's degree in Computer Science. He is a co-author of the book "New Pattern of Finance: Breakthroughs and Innovations in Asset Securitization," a mentor at Tsinghua University's School of Economics and Management, a member of the Strategic Consulting Committee for the MBA program at Tsinghua University's School of Economics and Management, and has published the paper "Exploration of the Application of Alliance Chain Technology in Asset Securitization Scenarios" in the Tsinghua Financial Review.
MD & Head, Weatlh and Retail Banking, Hong Kong
First joined the Bank in 1997
Stephen held various leadership roles in the Bank, including Regional Distribution, Wealth Management, Cross-Border, New Business Development, Deposit and Mortgage
MD & Head, Distribution, Wealth and Retail Banking, Hong Kong
Eliza looks after all branches and non-branch sales team
Through the 20 years within the Bank, she has covered areas in Wealth Management, Affluent Segment, Partnerships, Sales Management, and Human Resources in HK, Shanghai and Singapore
Eliza also spent 3 years in Mox Bank Ltd, where she was the Chief People Officer and was a member of the Management Committee
MD & Head, Wealth Solutions, Weatlh and Retail Banking, Hong Kong
First joined the Bank in 2022
Alson takes charge of the Wealth Solutions business covering managed investments, capital markets products, wealth advisory, bancassurance and wealth proposition for WRB
Prior joining the Bank, Alson previously worked as Head of Insurance for Citibank
Alson first joined Citibank in 2006 as a Management Associate and has led different wealth product teams including deposits, transaction banking, equities & FX trading and margin products. He also led the bank’s digital and partnership agenda and expanded digital wealth capabilities by launching the first bancassurance virtual selling process in the market.
ED, Head, Digital Sales and Acquisition, Weatlh and Retail Banking, Hong Kong
First joined the Bank in 2023
Herbert leads the digital sales transformation making it easier for people to discover and engage with WRB
Since joining, Herbert has brought forward digital-first strategies that drive performance marketing, personalization innovation, and Customer Lifecycle marketing to increase the strength of our customer’s digital relationship
Prior to joining the bank, Herbert previously worked as Head of Digital Marketing & Partnerships for Sun Life Financial Asia
President, ZA International
Mr. Xu joined ZhongAn Insurance in January 2014, serving as the Chief Operating Officer. Since the establishment of ZhongAn Technology (International) Group Co., Ltd. ("ZhongAn International") in December 2017, Mr. Xu has been the President of ZhongAn International and is currently also the Chief Executive Officer of ZA Insure, a fully digital insurance platform under ZhongAn International. Mr. Xu has over a decade of experience in the development and management of internet products. Prior to joining ZhongAn, he was a founding member of the Google China Product Management team.
Fintech Solution Consultant, Tencent Cloud
With over 15 years of experience in the financial industry, Kola Lyu has accrued a wealth of experience through his tenure at IBM, which spanned 8 years. During this time, he provided support to a diverse clientele of financial institutions based in Hong Kong and other international locations. Kola also contributed 7 years to FICO and Tencent, where he visited and engaged with over 100 financial institutions across China, thereby developing an in-depth comprehension of the distinct needs of these organizations. Currently, Kola Lyu is fully engaged in the endeavor to extend best practices to customers in the regions of South-East Asia, the Middle East, and Europe.
Expert of Financial Risk Control, Tencent Cloud
Peter is an expert in Financial Risk Control at TenDI, with extensive experience in fraud detection and credit risk management for the banking and lending industry. Previously worked as a modeling manager at Check Into Cash and senior data scientist at Axcess Financial in the United States. Peter is proficient in designing and implementing risk control systems for individual and corporate credit evaluation, dedicated to providing efficient and reliable risk control solutions for corporate clients.
Group Chief Strategy Officer, WeLab
Jessica Lam is the Group Chief Strategy Officer at WeLab, a prominent fintech company that ranks as one of Asia’s leading digital-native financial service brands with nearly 50 million individual users and over 700 enterprise customers across Hong Kong, Mainland China, and Indonesia. WeLab oversees one of Asia's largest digital consumer finance operations, a pan-Asian digital bank, and a top B2B fintech enterprise solutions provider. Jessica orchestrates the group's overall strategy and spearheaded the launch of WeLab Bank in Hong Kong in 2020. Before joining WeLab in 2017, she had a 12-year tenure at Goldman Sachs in Hong Kong, Singapore, and London, focusing on Investment Banking and Private Wealth Management. Additionally, Jessica serves as a Board Member of the FinTech Association of Hong Kong, which represents the city’s fintech sector on a global stage.
General Manager, The Fintech Association of Hong Kong
Raphael joined the FinTech Association of Hong Kong (FTAHK), Asia’s largest fintech association by membership, as General Manager in January 2022. He oversees the association with his Executive Team and collaborates with the Board, Co-Chairs, industry partners, and members to advance the FTAHK 2.0 strategy. Previously, Raphael spent over 15 years at Deutsche Bank in corporate and transaction banking, holding senior positions in corporate treasury advisory, market and client intelligence, and correspondent banking and clearing. He was integral to the bank's digital transformation in APAC, partnering with FinTechs in areas like blockchain, payments, eCommerce, and fraud detection. Raphael holds both a Bachelor's and Master’s Degree in European and Business Law from the University of Siegen, Germany.
Founder, Chairman and Chief Executive Officer
Philip Meyer is a seasoned global business leader with over 35 years in financial technology, payments, internet, and media industries. He founded Vaultavo Inc., a crypto asset custody solutions provider, in April 2021 and serves as its Chairman and CEO. Meyer also founded Transact24 Ltd. in 2006, a global payments company, and held the role of managing director for nearly 15 years. Previously, he was the Group CEO of Ceevo, overseeing operations across international payment subsidiaries within Net 1 UEPS Technologies. His early career included significant roles at uc Group and Naspers, where he launched several successful digital platforms, including 24.com.

Co Founder, Mantra and Soma finance
John Patrick Mullin is an entrepreneur based in Hong Kong, specializing in DeFi, blockchain, and Web3 as the CEO and co-founder of MANTRA and SOMA.finance. Introduced to Bitcoin in 2013 while studying International Business at SLU-Madrid, John's career evolved from a senior research analyst at a major Chinese bank to pioneering early crypto exchange projects in Hong Kong. His ventures, MANTRA and SOMA.finance, focus on blockchain innovation and have raised tens of millions of dollars. John is also a noted speaker at top global universities including Harvard and the London Business School.
Advanced Risk Management and Regulatory Strategy
Brian Lo is a seasoned risk professional with nearly 30 years of leadership experience in global and regional financial institutions. Most recently, he served as Managing Director and Group Head of Market and Liquidity Risk at DBS Bank, where he led a team across Asia, Europe and Australia in managing market, liquidity and counterparty risk, asset and liability management, and regulatory engagement. His expertise includes quantitative modelling, stress testing, and the strategic application of AI and machine learning in risk management. Earlier in his career, Brian held senior risk roles at BNP Paribas and Citibank. He has served on multiple risk committees and regulatory taskforces, playing a key role in implementing Basel reforms and developing internal capital and liquidity frameworks.
Digital and Technology Strategy
Axel Winter is a highly experienced technology leader with strong hands-on experience in the banking, retail and start-up worlds. He was previously Global Head of Enterprise Architecture and Technology Strategy for Standard Chartered Bank and held similar roles at GE Money and Cisco Systems. He has consulting experience at Accenture and Deloitte, and has recently founded a corporate start-up partnering with Grab and JD.com. He is currently Chief Digital Officer for a luxury mall operator and advises start-ups in asset tokenisation and eCommerce. His expertise in technology infrastructure for banks and large businesses makes him a valued contributor across digital and AI-focused programmes.
Banking Strategy, Financial Policy and Capital Markets
Nick Dove holds a PhD from Cambridge University and became a bank analyst and executive director at UBS, where he advised bank management on strategy and equity issuance, and senior fund managers on investment strategy. His team was ranked the best European all-sector research team by fund managers. Since leaving UBS, Dove has advised governments, development agencies and financial institutions on banking, private sector development and the impact of regulation. He has written reports on sovereign wealth funds, infrastructure investment and de-risking. He runs executive training courses on management development, is a director of a London-based hedge fund with a concentration of investments in financial institutions, and is a trustee of a charity focused on job creation in Sub-Saharan Africa.
Banking Simulation and International Finance
Anoop Rai is a Professor of Finance at the Frank G. Zarb School of Business at Hofstra University, New York, where he teaches corporate finance, international finance and risk management. He is a partner at ProBanker Simulations, which develops training simulations for universities and corporate programmes. With over 20 years of experience using simulations as a teaching tool, his research focuses on international finance, banking and global regulation. Professor Rai is Associate Editor of the Journal of Multinational Financial Management and co-author of two textbooks — Principles of Banking and Basics of International Business. He has lectured at several universities and conducted training seminars for financial institutions across Europe, Asia and the Middle East.
Financial Policy and Systemic Risk
Mark D. Flood is a Visiting Research Scholar in the Center for Financial Policy at the University of Maryland's Smith School of Business. From 2020 to 2024 he was a programme manager at DARPA's Information Innovation Office. He has taught finance in the United States and Canada and spent over two decades in financial policy and regulation at the Federal Reserve Bank of St Louis, the Office of Thrift Supervision, the Federal Housing Finance Board, the Federal Housing Finance Agency, and the Office of Financial Research at the US Department of the Treasury. His work bridges quantitative finance, regulatory design and the policy implications of emerging technology for financial institutions.
Investment Consulting and Financial Services Advisory
Gordian Gaeta has been an investment consultant for more than 25 years. He has advised and served many of the leading financial services organisations across Asia and close to half of the top 100 banks worldwide. He specialises in developing and implementing analytical solutions for complex strategic issues in financial services-related industries undergoing significant change or being exposed to intricate risk issues. He is currently the principal of Leopard Capital. As chairman, he convenes the advisory boards that validate the matrices used in programme ratings, rankings and awards to ensure they are conducted in a professional, impartial and accountable manner.
ESG and Impact Investing
Robert Rubinstein is Chairman and Founder of TBLI Group, a leading global ESG and impact investing network with 25 years of experience educating, advising and connecting investors. He taught courses in sustainable finance at the Rotterdam School of Management from 2003 to 2006 and has delivered lectures at international business schools and universities throughout his career. He is a member of the Advisory Council for Wealth and Society and contributes to Banking Academy programmes on impact investing, sustainable finance and the ESG accountability frameworks that institutional investors are applying to banking.
Digital Retail Banking
Wilson Chia is one of the most experienced digital bankers in the world, with over 30 years as a career banker, mostly in international positions at Standard Chartered Bank. He currently advises the chief executives of leading banks in emerging markets on digitalising traditional business lines. His strong financial background and expertise in balance sheet management, funding and product disciplines make him a valuable contributor across the Academy's retail and digital banking programmes.
SME Banking, Credit and Risk Management
Andrew McRobert is a credit and risk management specialist in development, commercial and SME banking. He currently runs a training and consulting firm in SME and small business banking. He started his banking career at Citicorp and has held various positions in commercial banking. Andrew also worked in corporate finance at Price Waterhouse in Jakarta, and has undertaken credit, problem loans and risk management assignments for the Asian Development Bank, IFC, African Development Bank and others. He has designed, written and presented financial markets seminars in nearly 30 countries across Asia Pacific, the Middle East and Africa. He is an advisor to the Excellence in Retail Financial Services Awards Programme at The Asian Banker.